Buy-to-Let Mortgages in Leicester
Personal buy-to-let, limited company BTL, first-time landlord borrowing and portfolio refinancing, we explain the options honestly and match your case to lenders whose criteria genuinely fit.
BUY-TO-LET MORTGAGES IN LEICESTER - OVERVIEW
What a buy-to-let mortgage is
A buy-to-let mortgage is designed for residential property let to tenants rather than lived in by the borrower. It sits in its own regulatory space, most BTL mortgages are not regulated by the Financial Conduct Authority, which is worth understanding at the outset.
How BTL differs from a residential mortgage
Compared with residential lending, BTL typically requires a larger deposit, is often arranged on an interest-only basis, and is assessed primarily on rental income rather than personal earnings. Lender criteria vary widely and can change quickly, especially around minimum income requirements and stress tests.
Deposit expectations
Most BTL lenders look for at least 25% deposit. Some will consider 20% for stronger cases, while others prefer 30% or 40% for better rates and easier stress-test outcomes. Larger deposits also open up specialist lenders and more flexible structures.
Rental income calculations
Rental income is the backbone of the affordability assessment. Lenders usually require the achievable monthly rent to cover 125% to 145% of the mortgage interest, stressed at a notional rate. The exact percentages depend on the borrower's tax position and the product chosen.
Interest-only and repayment options
Interest-only keeps monthly payments low and cashflow strong, but the capital still needs repaying at the end of the term, usually through sale or refinance. Repayment reduces the balance over time. Many landlords use a mix across their portfolio, depending on strategy.
First-time landlords
First-time landlords have fewer lender options and often need to already own their own home. Some lenders also apply minimum personal income requirements. We help first-time landlords in Leicester understand what's genuinely achievable and target lenders where they'll be welcomed rather than politely declined.
Limited company buy-to-let considerations
Limited company BTL has become increasingly common, particularly for higher-rate taxpayers. It can offer tax benefits but involves higher product costs, more paperwork and additional annual administration. It is a tax decision as much as a mortgage one, so an accountant's input is important.
Buying personally or through a company
The right structure depends on your tax position, other income, plans for the portfolio and your appetite for administration. There is no universally correct answer, and structures aren't always straightforward to unwind, so getting appropriate advice from an accountant is essential before deciding.
Common costs beyond the mortgage
- Stamp Duty Land Tax at higher additional-property rates
- Solicitor / conveyancer fees and disbursements
- Valuation and any additional survey work
- Lender arrangement or product fees
- Landlord insurance, safety certificates and letting agent fees
- Ongoing maintenance and provision for void periods
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
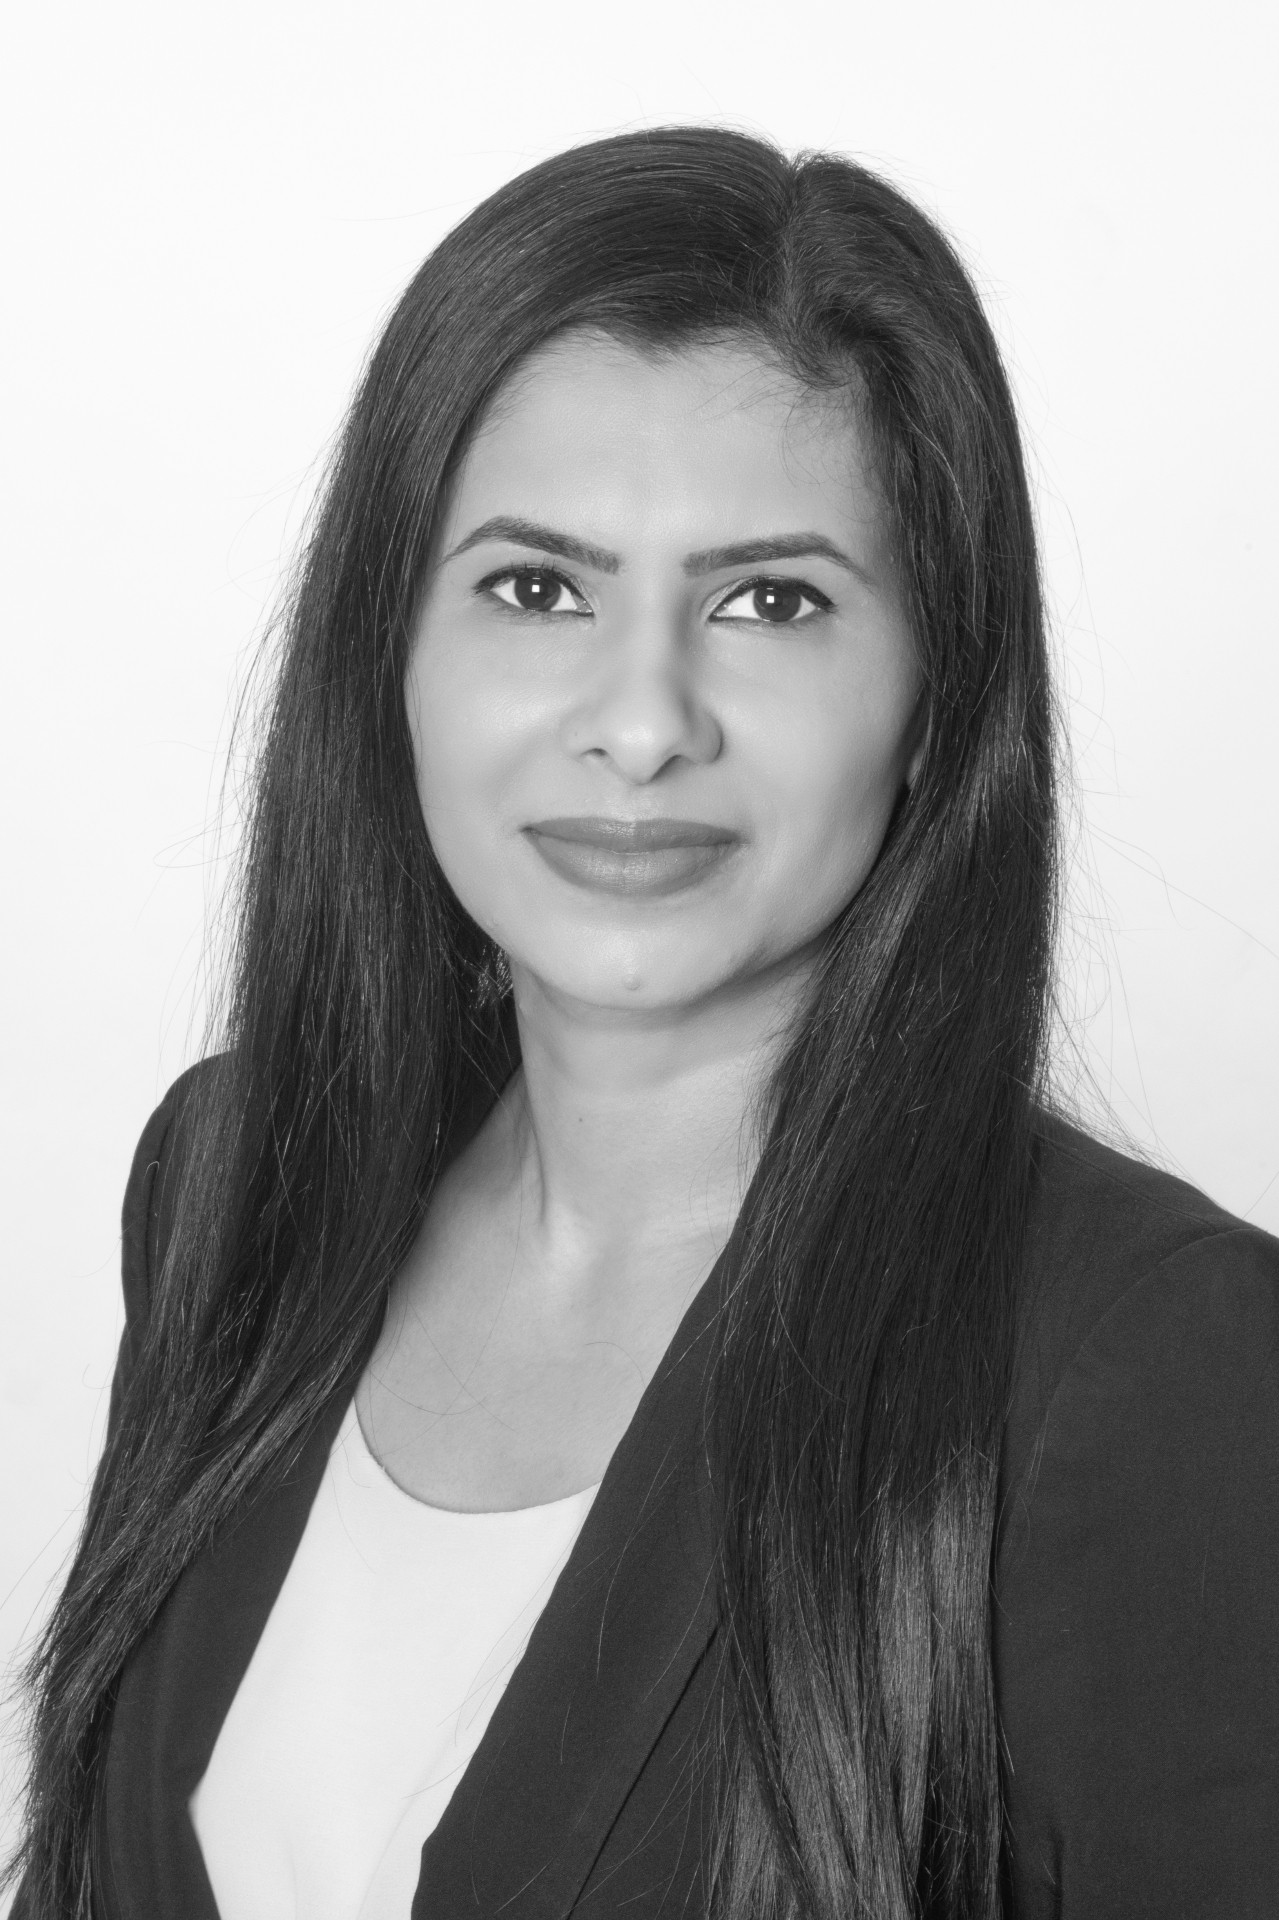
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
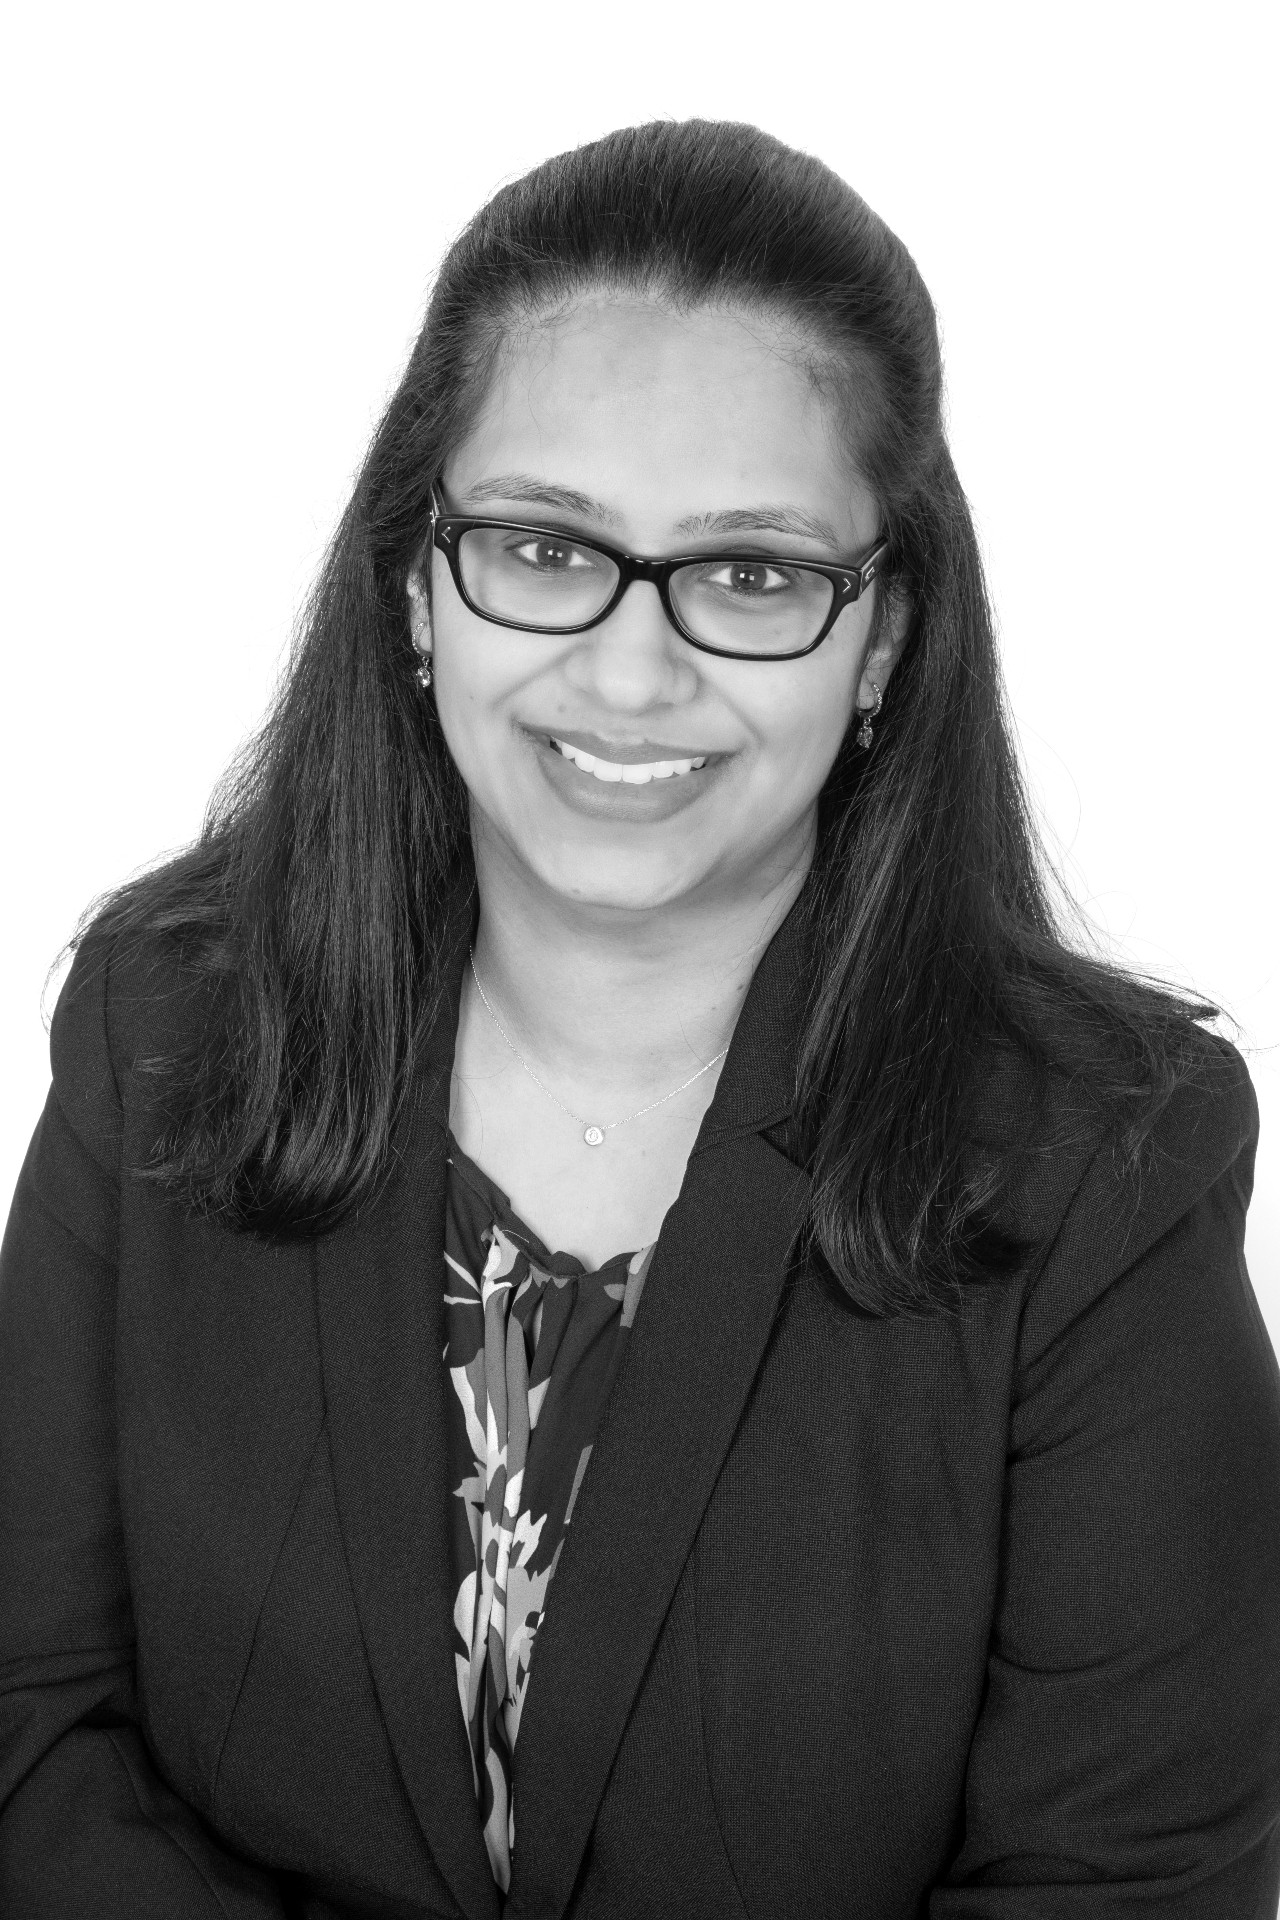
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Frequently Asked Questions
How is a buy-to-let mortgage different from a residential mortgage?
A buy-to-let mortgage is specifically designed for property let to tenants rather than lived in by the borrower themselves. Deposits are usually larger, interest-only options are common, and lender criteria focus heavily on projected rental income levels. Many buy-to-let mortgages are unregulated, so the consumer protections around residential lending do not necessarily apply to them.
How much deposit do I need for a buy-to-let?
Most buy-to-let lenders look for at least a 25% deposit, though 20% may be possible with some lenders and stronger cases benefit from 30 to 40%. A larger deposit tends to unlock better rates and pass rental income stress tests more easily. We will help you understand what is realistic based on the specific property.
Can I get a buy-to-let mortgage as a first-time landlord?
Yes, though the choice of lenders is narrower. Some lenders also prefer first-time landlords to already own their own home. Personal income, deposit and rental income all matter. Bina and Tajal will look at your position honestly and identify lenders whose criteria genuinely fit your circumstances as a new landlord in Leicester.
Is interest-only better than repayment on buy-to-let?
Interest-only is very common on buy-to-let because it keeps monthly costs lower and can improve cashflow. However, the capital still needs repaying at the end of the term, usually through sale or refinance. Repayment reduces the balance over time. We will discuss which option better suits your long-term plans and overall investment strategy.
Should I buy through a limited company or personally?
This depends on your tax position, existing income, plans and portfolio size. Limited company structures can suit higher-rate taxpayers or portfolio landlords, but they carry more cost and complexity. We advise on the mortgage side and will always recommend speaking with a qualified accountant before deciding how to structure a buy-to-let purchase or portfolio.
What other costs should I plan for beyond the mortgage?
Beyond the deposit and mortgage costs, budget for stamp duty (often at higher additional-property rates), legal fees, valuation, potential refurbishment, landlord insurance, safety certificates, letting agent fees and ongoing maintenance. Void periods and unexpected repairs also need factoring in. We will help you look at the whole picture, not just the monthly repayment.