Financial Protection Advice in Leicester
Sensible, jargon-free protection advice so that your income, your family and your home are looked after if life takes an unexpected turn.
FINANCIAL PROTECTION ADVICE IN LEICESTER - OVERVIEW
Why protection matters
Most households insure their car, their phone and their pet, yet leave the biggest asset of all, their ability to earn, completely uninsured. Financial protection puts that right, giving you a plan for the moments when life doesn't go as expected.
Income protection
Income protection pays a regular, tax-free monthly benefit if you can't work due to illness or injury. It's designed to replace a proportion of your income for as long as you need it, up to the policy's ceasing age.
Mortgage protection
Mortgage protection is arranged to cover your mortgage balance if you die or, on some policies, are diagnosed with a serious illness during the term. It's often the first protection homeowners consider, and one of the most valuable.
Critical illness cover
Critical illness cover pays a tax-free lump sum if you're diagnosed with one of a defined list of serious conditions, such as certain cancers, heart attack or stroke. It can be arranged alongside life insurance or as a standalone policy.
Life insurance
Life insurance pays a lump sum, or provides a family income, if you pass away during the policy term. It's a straightforward, cost-effective way to protect the people who depend on you financially.
Choosing the right cover
The right mix depends on your income, family, mortgage, existing employer benefits and personal priorities. We take the time to understand these before recommending anything, then explain clearly why we suggest the cover we do.
How much cover costs
Premiums depend on age, health, lifestyle, cover amount and term. Getting cover in place earlier is usually cheaper. We will always show you a range of options at different price points, so you can choose what feels affordable and sustainable.
Writing policies in trust
Placing a life policy in trust can help the pay-out reach your loved ones quickly and, in many cases, outside your estate for inheritance tax purposes. We'll explain when this is appropriate and help arrange it where suitable.
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
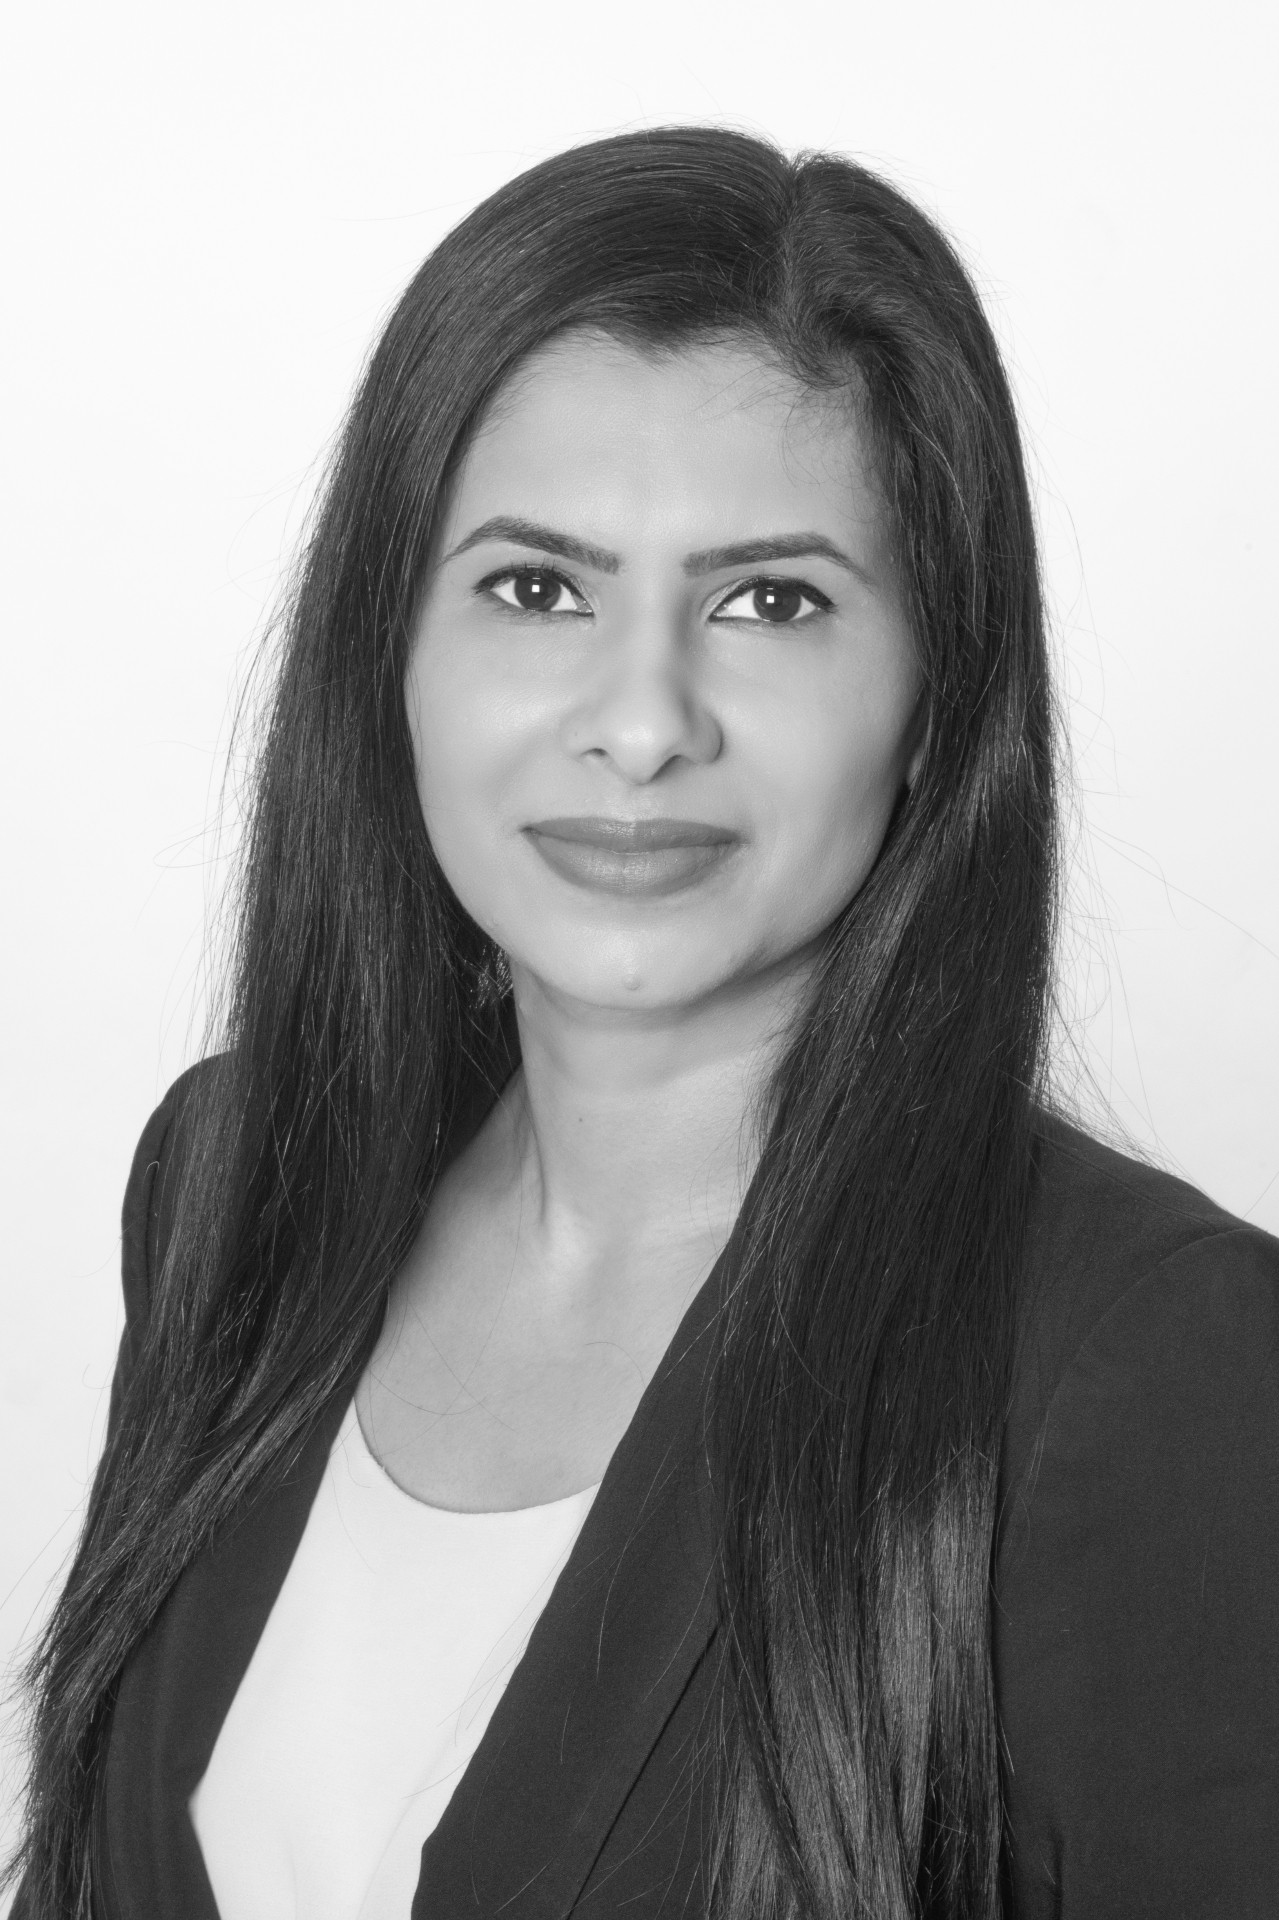
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
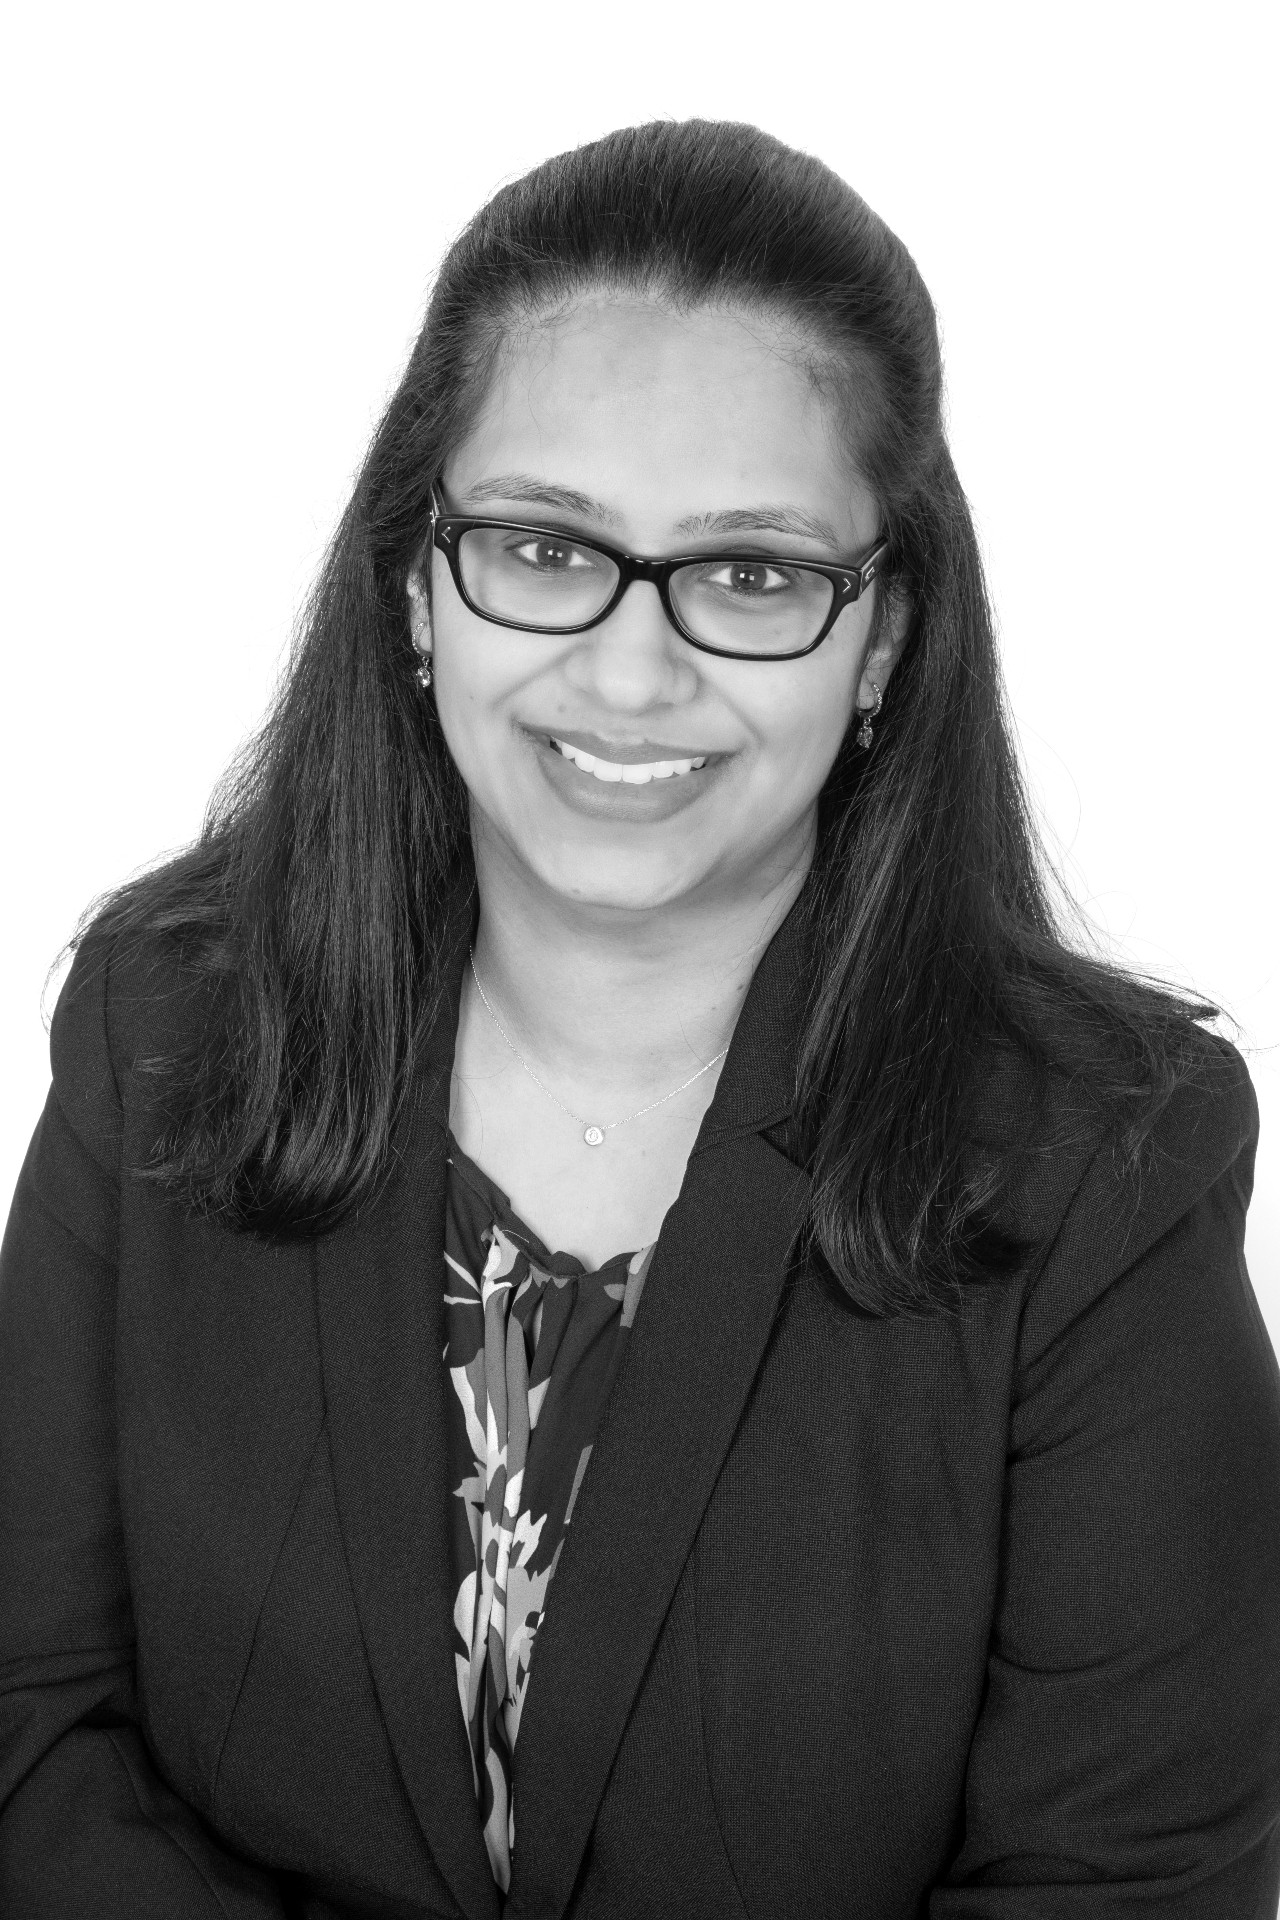
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Income Protection
Protecting your monthly income if you can't work.
Read moreMortgage Protection
Cover designed around your mortgage balance and term.
Read moreCritical Illness Cover
A lump sum on diagnosis of a serious illness.
Read moreLife Insurance
Financial protection for the people who depend on you.
Read moreFrequently Asked Questions
What is financial protection?
Financial protection is a group of insurance-based products designed to protect your income, mortgage and loved ones if you become ill, unable to work or pass away. It typically includes life insurance, mortgage protection, critical illness cover and income protection. The right mix depends on your circumstances, budget and priorities, and independent advice helps you get that balance right.
Which type of cover do I need first?
There is no single answer. For most homeowners with a mortgage and dependants, life cover and income protection are usually the starting points, with critical illness cover often added where budget allows. We take time to understand your family, income and existing employer benefits before recommending anything, so the plan genuinely fits your situation.
Can I arrange protection alongside my mortgage?
Yes, and it is often the most natural time to review it. When we advise on your mortgage, we will always offer to look at protection at the same time. Cover can be arranged to match your mortgage term and balance, so the two work together sensibly rather than being reviewed in isolation years later.
Do I need protection if my employer already provides some cover?
Employer benefits vary considerably and often stop if you leave, retire or are made redundant. It is worth checking exactly what your employer provides, for how long, and under what conditions. We can review your existing benefits and recommend where a personal policy is needed to give you meaningful protection you can rely on long-term.
Will my medical history affect my premiums?
It can. Insurers ask health, lifestyle and family history questions and price accordingly. Being honest and accurate on the application is essential, as non-disclosure can invalidate a claim. Where medical history is more complex, we know which insurers tend to take a more considered view and will target your application accordingly for the best outcome.
Do you charge for protection advice?
Our protection advice is usually paid for by commission from the insurer, at no additional cost to you. We will always explain fully how we are remunerated before you commit, including any fee that may apply in more complex cases. Any fees will be agreed clearly and in writing upfront before any chargeable work is carried out.