Equity Release and Later Life Lending in Leicester
Careful, balanced advice on later-life mortgage options, including lifetime mortgages, RIO mortgages and standard later-life residential borrowing. We take time to understand your goals and the impact on your estate and family.
EQUITY RELEASE AND LATER LIFE LENDING IN LEICESTER - OVERVIEW
What later-life lending means
Later-life lending is an umbrella term for borrowing options designed to work in retirement or in the run-up to it. It includes lifetime mortgages (the most common form of equity release), retirement interest-only (RIO) mortgages and standard residential mortgages with later-life-friendly criteria.
Equity release, lifetime mortgages, later-life residential mortgages and RIO
Lifetime mortgages (equity release) usually have no compulsory monthly payments, with interest rolling up and the loan repaid from the sale of the home. RIO mortgages require monthly interest payments and are assessed on retirement income. Later-life residential mortgagesare standard mortgages arranged with lenders willing to lend later into life.
Staying in your home
For most people, a central goal of later-life borrowing is being able to stay in the home they know and love. Each option supports that in different ways, and there are usually trade-offs to weigh between monthly affordability, long-term cost and the eventual value passed to family.
Releasing funds versus continuing mortgage borrowing
Some clients need to release capital, for home improvements, family support, or clearing existing debts. Others simply want to continue managing an existing mortgage into and through retirement. The right answer depends on your income, plans, family situation and appetite for future flexibility.
Monthly payments and no-payment options
Standard and RIO mortgages require ongoing payments. Lifetime mortgages typically don't, though many modern plans allow voluntary partial repayments. We'll walk you through the practical differences in monthly cashflow, long-term cost and estate impact so you can decide with full clarity.
Effect on inheritance
Any borrowing secured against your home reduces the value that will eventually pass to your beneficiaries. This is often a significant consideration for families, and we encourage open conversations early, so any decision reflects the wider picture rather than just the immediate need.
Potential impact on means-tested benefits
Releasing money from your home may affect entitlement to means-tested benefits, such as Pension Credit or Council Tax Support. As part of our advice process, we'll discuss any such impact openly and factor it into the recommendation.
The importance of considering alternatives
Later-life borrowing is not always the right answer. Alternatives include downsizing, using savings or investments, family support, or state benefits you may not currently be claiming. We look at these options openly before recommending any form of later-life lending.
Involving family members
Where appropriate, we strongly encourage clients to involve family. Later-life decisions have implications for those close to you, and open conversations help avoid surprises later. Bina and Tajal are very comfortable with family joining meetings when clients would like them present.
Need for legal and independent financial advice
Equity release plans that meet Equity Release Council standards require independent legal advice, and we'll help you plan the timings sensibly. Where wider financial planning matters, we can work alongside your financial planner or introduce you to one.
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
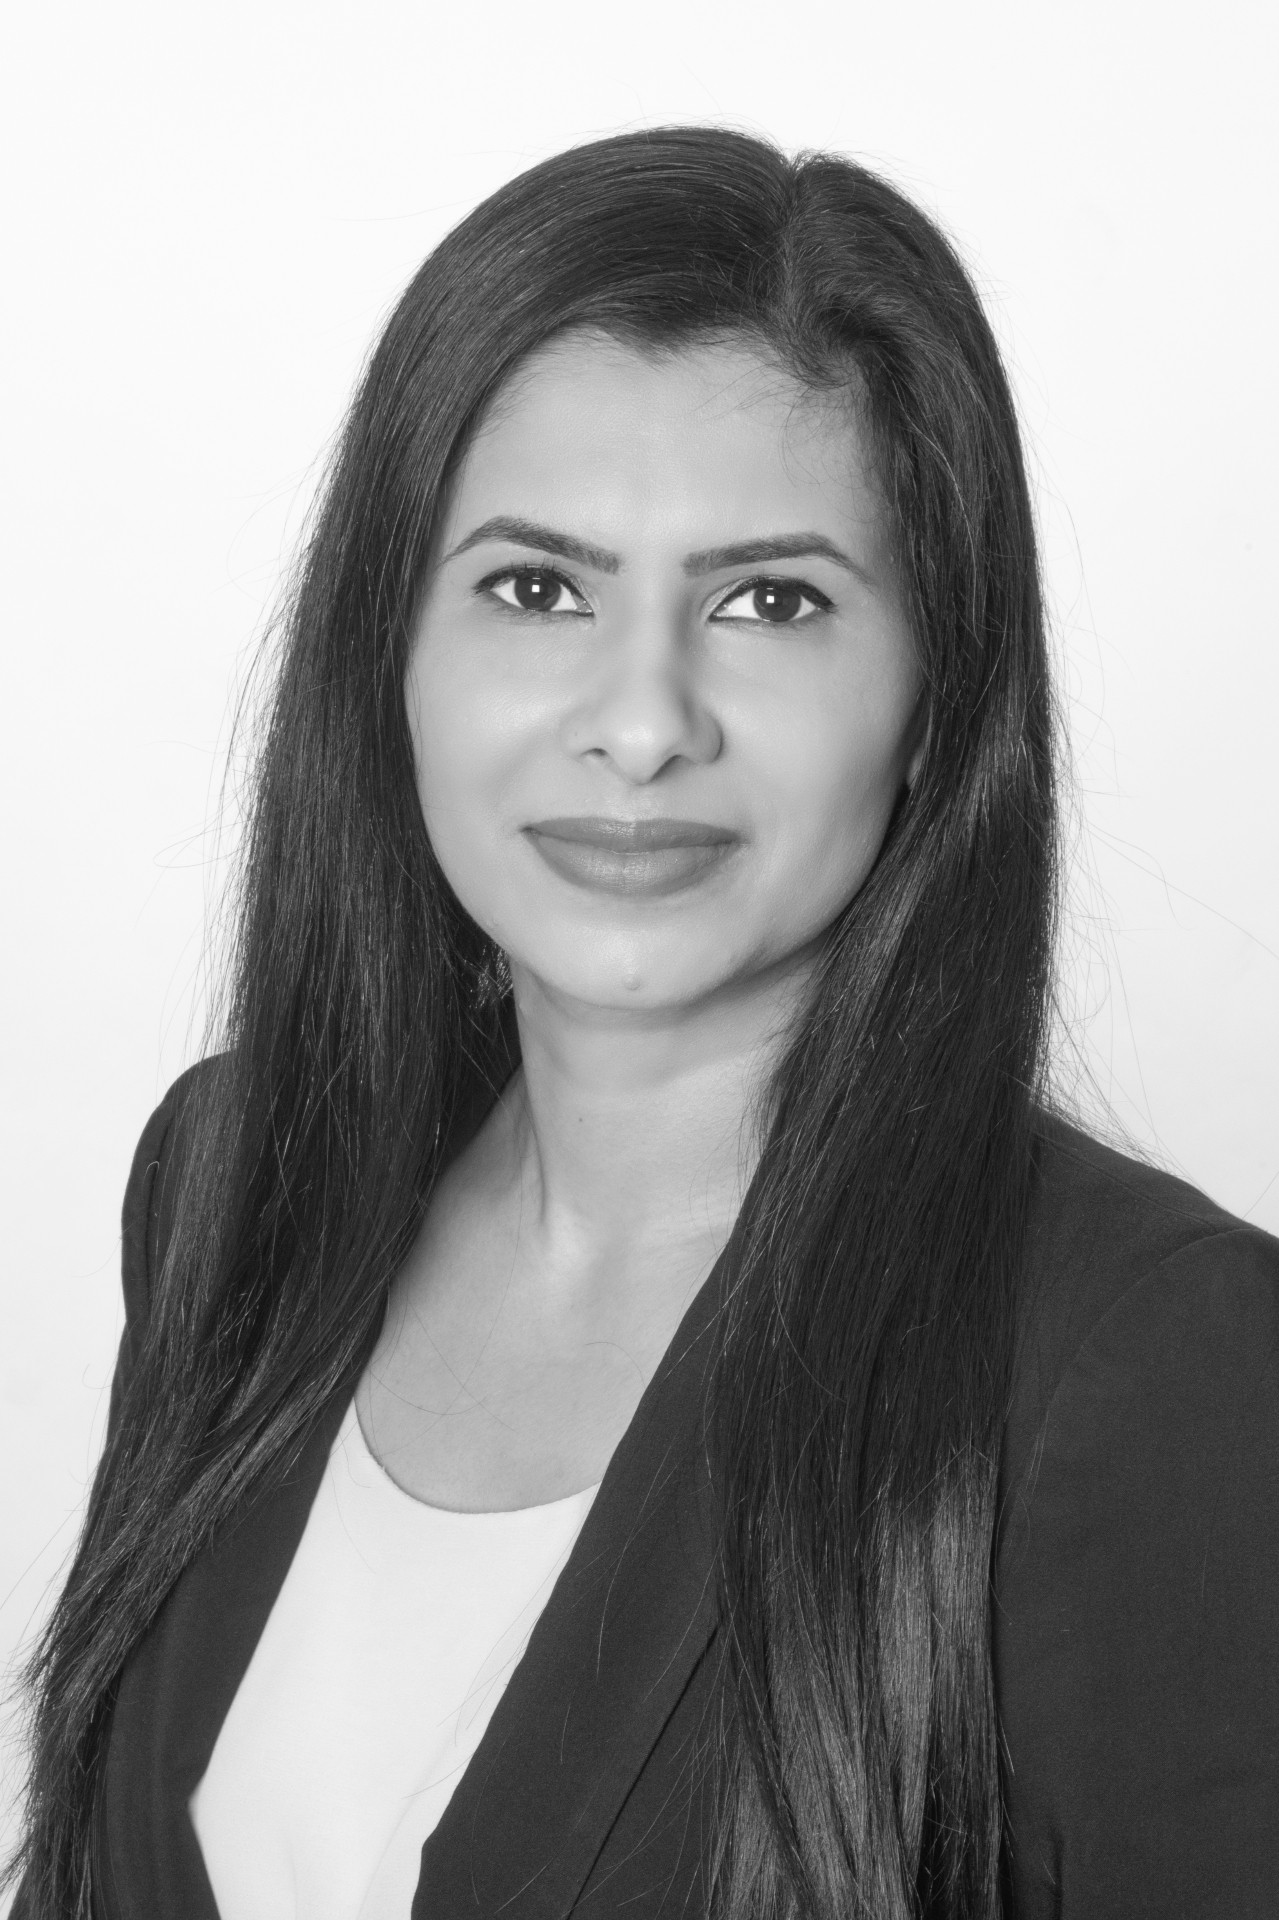
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
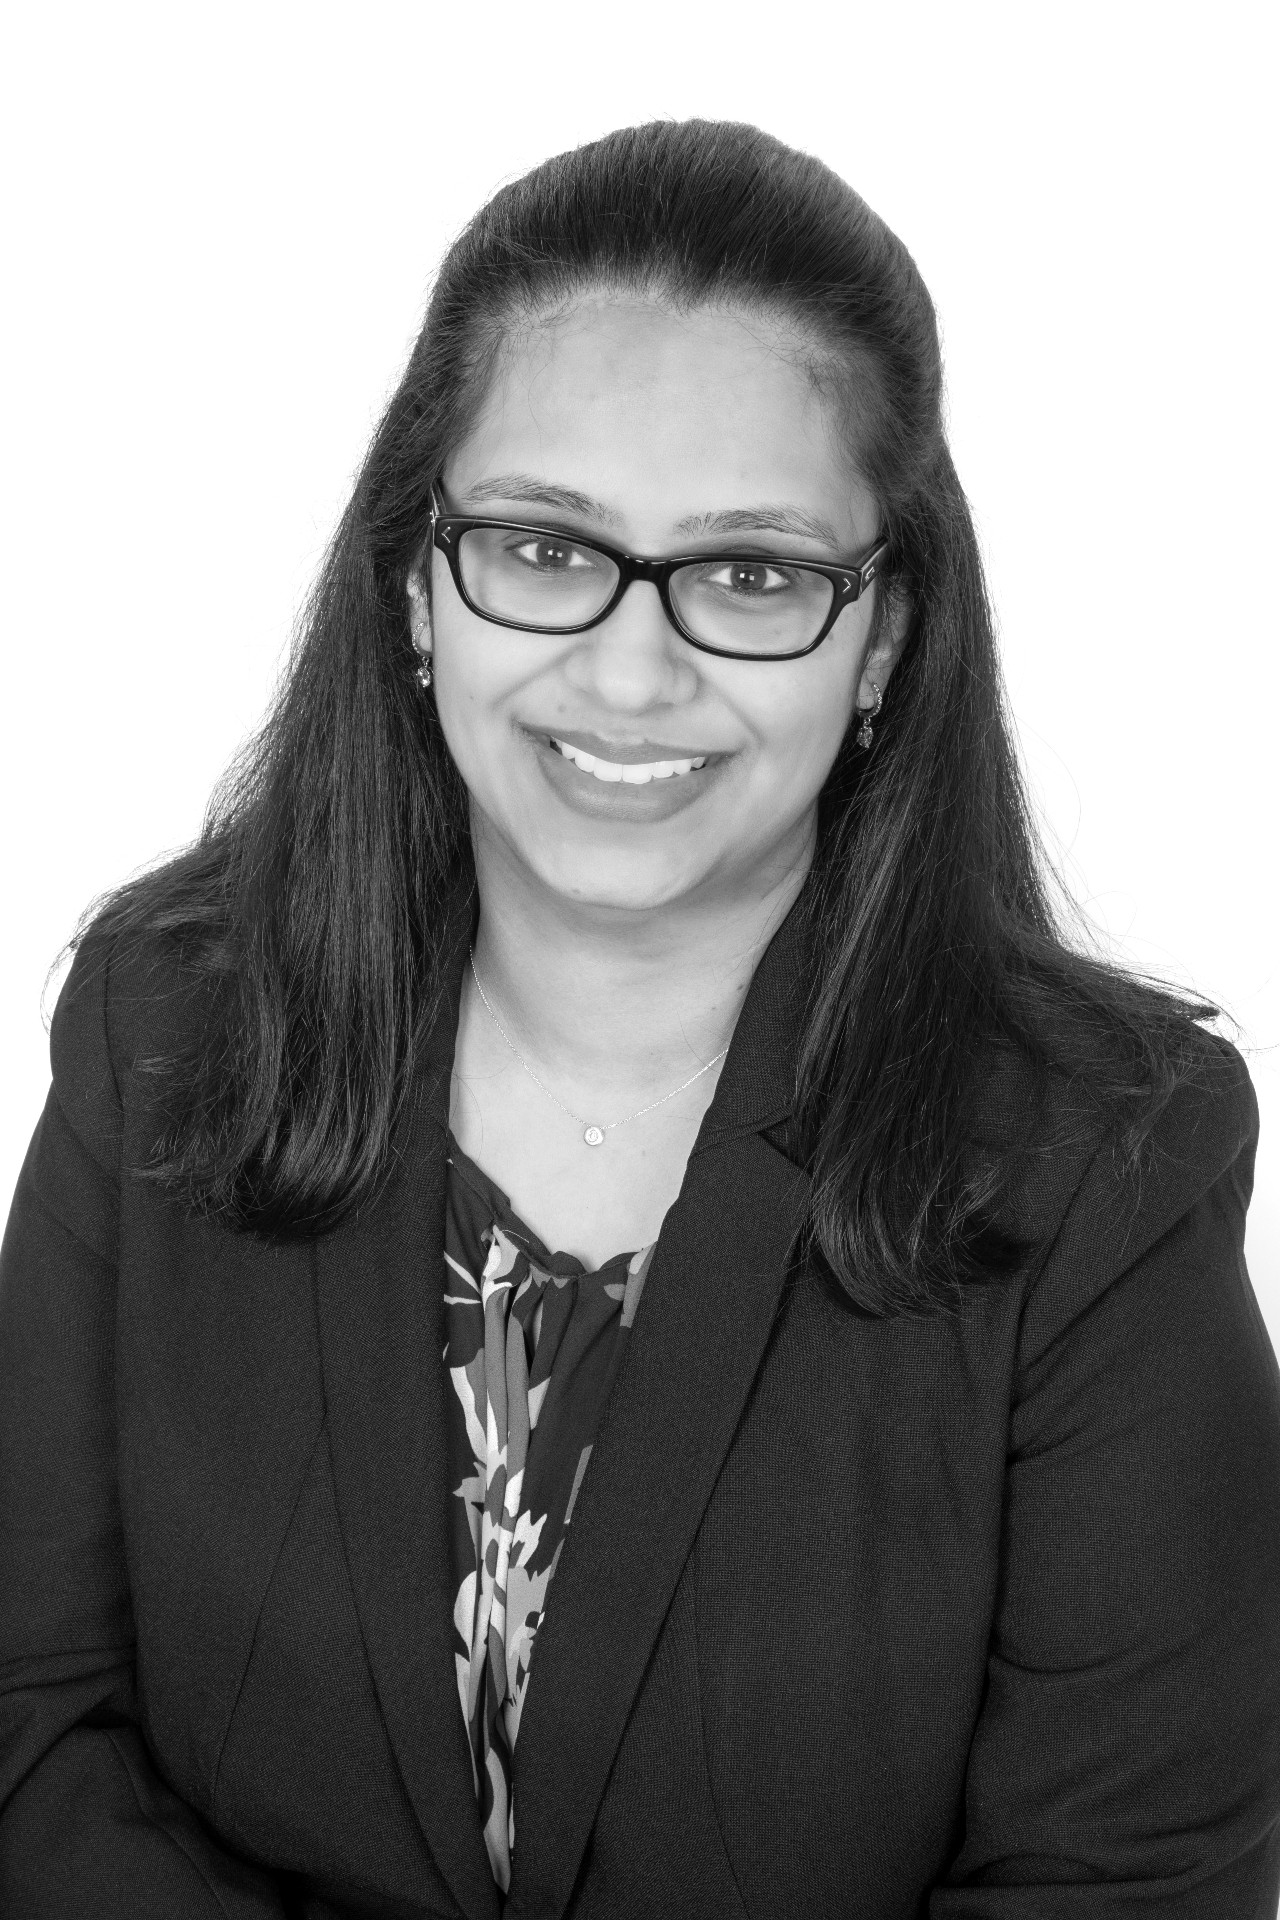
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Frequently Asked Questions
What is later-life lending?
Later-life lending is a general term for borrowing options aimed at people usually aged 55 and over. It includes equity release, lifetime mortgages, retirement interest-only (RIO) mortgages and standard residential mortgages with later-life-friendly criteria. Each works quite differently, and choosing between them properly requires balanced, regulated advice from a qualified later-life mortgage adviser.
How is equity release different from a normal mortgage?
With a standard mortgage you make monthly payments and repay the loan over a set term. With equity release, usually a lifetime mortgage, there are typically no compulsory monthly payments and the loan plus rolled-up interest is repaid when you die or move into long-term care. Both routes have quite different long-term implications for your estate.
Will equity release affect my inheritance?
Yes, it can. Any equity released, plus accumulated interest, is repaid from the value of your home, which reduces what remains for your estate. Some plans include inheritance protection features to ring-fence a portion of value. We will explain these options carefully and encourage you to involve your family in the conversation where appropriate.
Could equity release affect my benefits?
Yes. Releasing money from your home may affect your entitlement to means-tested benefits such as Pension Credit or Council Tax Support. This is why balanced, regulated advice matters. As part of our advice process, we will consider the potential impact on any means-tested benefits you receive and discuss it openly with you before recommending anything.
Should I involve my family in the decision?
We strongly encourage it. Later-life lending decisions affect not only you but also your wider family, particularly around inheritance and future care planning. Involving family early avoids surprises later and lets everyone ask questions. Bina and Tajal are very comfortable involving loved ones in meetings when clients would like them present.
Do I need legal advice for equity release?
Yes. Independent legal advice is required for equity release plans that meet Equity Release Council standards. Your solicitor works separately from the adviser, protects your interests and confirms you understand what you are entering into. We will explain what to expect from the legal side and help you plan the timings sensibly around the application.