Remortgage Advice in Leicester
Whether your fixed rate is ending, you're raising capital or your circumstances have changed, we help you review your options clearly and choose the most suitable route forward.
REMORTGAGE ADVICE IN LEICESTER - OVERVIEW
What remortgaging means
Remortgaging means moving your existing mortgage to a new deal, either by staying with your current lender (a product transfer) or switching to a different one (a full remortgage). People remortgage to secure a better rate, restructure their borrowing, raise capital, or change the term of the loan.
When to start reviewing
The sensible starting point is around six months before your current fixed or discounted rate ends. That gives us enough time to compare options, secure a new rate without paying an early repayment charge, and avoid landing on your lender's standard variable rate unnecessarily.
Fixed-rate expiry
When a fixed rate ends, most lenders automatically move you onto their standard variable rate (SVR), which is often significantly higher than the deals available. A timely review helps you avoid this and keep monthly payments predictable.
Product transfer vs remortgage
A product transfer is simpler and typically involves less paperwork, since you're staying with your existing lender. A full remortgage means moving lender, which can open up better rates, more borrowing or improved features. We compare both and recommend the option that best fits your circumstances.
Raising capital
Homeowners sometimes remortgage to release equity for major expenses, such as home improvements, family support or life events. Lenders will assess affordability and the reason for the additional borrowing, and the loan-to-value must still fit their criteria.
Debt consolidation
Consolidating unsecured debts into a mortgage can reduce monthly outgoings, but it also secures those debts against your home and usually extends the repayment term, increasing the total interest paid over time. It isn't automatically right or wrong , we'll explain the trade-offs carefully so you can decide with full clarity.
Home improvements
Funding an extension, refurbishment or major home improvement through a remortgage or further advance can be a practical way to finance the work, particularly if it will add value to the property. Lenders will still assess affordability against the full new borrowing amount.
Changes in income or circumstances
Life doesn't stand still. A new job, self-employment, a growing family, or a change in household structure can all affect your mortgage. A remortgage review is a natural moment to reassess whether your current arrangement still fits.
Standard variable rate considerations
Standard variable rates aren't automatically the wrong place to be, they can offer flexibility, and for some borrowers the freedom to overpay or repay without early repayment charges is useful. But they are usually more expensive than a reviewed fixed or tracker product, so it's worth considering the alternatives.
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
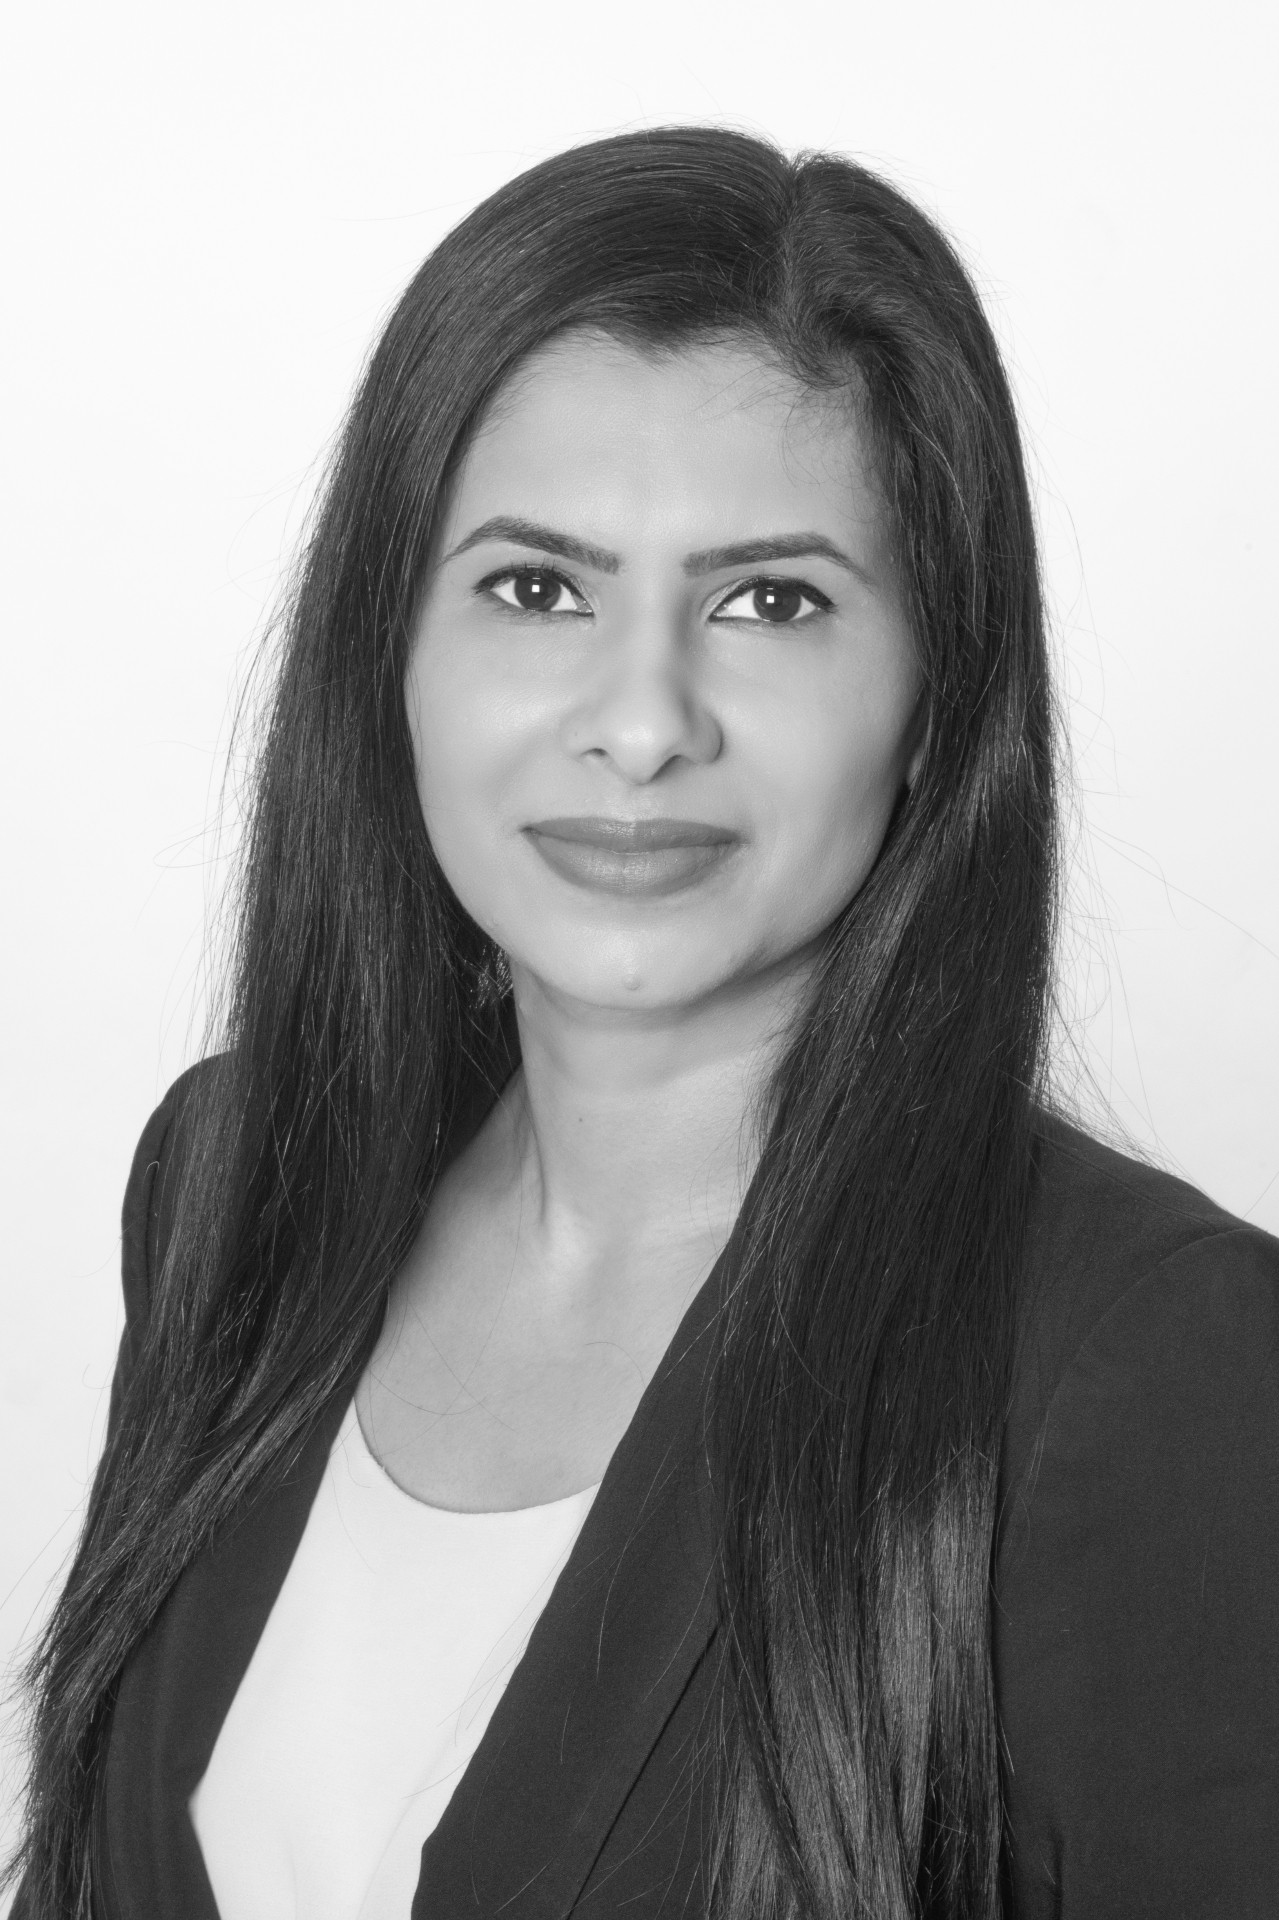
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
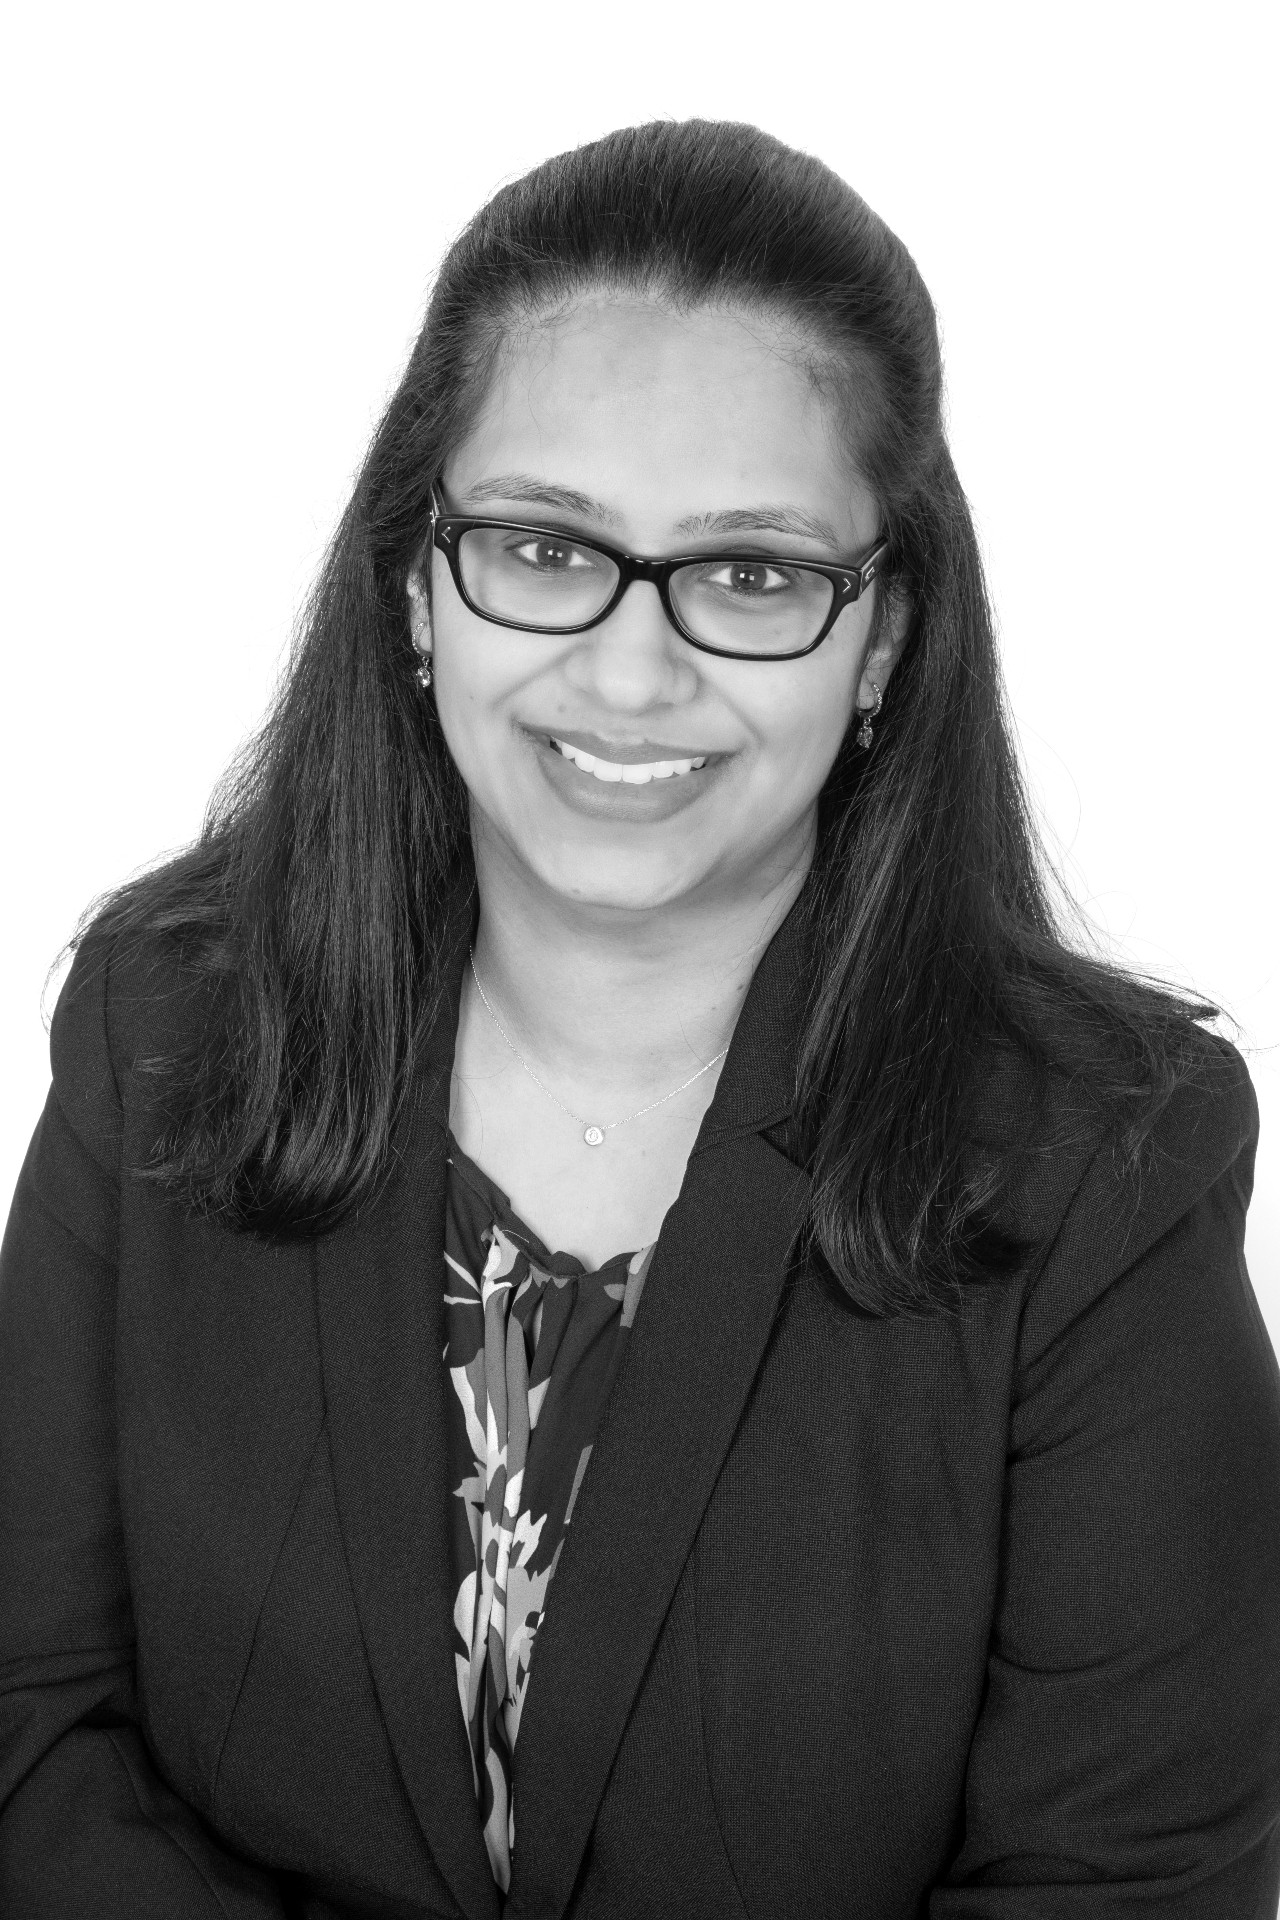
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Frequently Asked Questions
What does remortgaging actually mean?
Remortgaging means moving your existing mortgage to a new deal, either with your current lender or a different one. People remortgage to secure a better rate, restructure their borrowing, raise capital or change the mortgage term. It is a normal part of managing your mortgage well over its full lifetime and staying on suitable terms.
When should I start looking at remortgage options?
Around six months before your current fixed or discounted rate ends is a sensible time to start reviewing. That gives us time to compare options and secure a new rate without paying an early repayment charge on your existing deal. Leaving it too late can push you onto a lender's standard variable rate unnecessarily for a period.
What is the difference between a product transfer and a remortgage?
A product transfer keeps you with your current lender on a new rate, usually with less paperwork. A remortgage moves you to a different lender, which may unlock better rates, more borrowing or improved terms. We compare both routes and recommend the option that fits your circumstances most closely at the point of your rate review.
Can I remortgage to raise capital?
Often, yes. Homeowners remortgage to release equity for home improvements, major life expenses or occasionally to consolidate other debts. Lenders will assess affordability and the reason for the additional borrowing. Where debt consolidation is involved, we will explain the risks carefully, since securing previously unsecured debts against your home is a serious step.
Will remortgaging affect my credit score?
A new mortgage application involves a full credit check, which leaves a footprint on your credit file. This is normal and rarely a problem in isolation. Making multiple mortgage applications in a short space of time can look less positive. Working with an adviser helps focus applications on lenders where you are likely to be accepted.
What if my property value has changed?
Property value directly affects your loan-to-value ratio, which influences the rates and products available to you. A higher value or reduced balance can unlock better deals; a lower value can restrict choices. We will discuss a realistic view of your current position before recommending the most appropriate remortgage or product transfer for your circumstances.