Mortgages for Property Investors
Structured finance advice for active investors, from single buy-to-let purchases and HMO borrowing to portfolio remortgages, semi-commercial property and limited company structures.
MORTGAGES FOR PROPERTY INVESTORS - OVERVIEW
Finance for growing property portfolios
Growing a portfolio well is often as much about lender selection and structure as it is about picking the right properties. Concentrating too much borrowing with one lender can restrict future choices, while spreading lending sensibly can preserve flexibility as the portfolio evolves.
Residential investment property
Standard residential buy-to-let remains the backbone of many portfolios. Lender criteria differ around minimum income, property type, tenant type, HMO status and landlord experience. We'll match your specific case to lenders where the criteria fit genuinely, not just marginally.
Buy-to-let investment finance
Investment BTL applies the same principles as standard buy-to-let but is often structured with a longer-term investment mindset. Interest-only borrowing, portfolio fit and product features around overpayments and early repayment charges become more important as the strategy scales.
Commercial and semi-commercial property
Semi-commercial property, such as a shop with a flat above, sits between residential and commercial lending. Fewer lenders operate in this space, and criteria vary substantially. Advice matters even more here, as does presenting the case clearly and completely.
Portfolio borrowing
Portfolio borrowing can consolidate multiple properties into a single arrangement with a specialist lender, or maintain separate mortgages per property with better product-level flexibility. The right choice depends on scale, gearing and long-term plans.
Limited company structures
Special purpose vehicles (SPVs) for holding property have become common. They can offer tax efficiency for some investors but bring more cost and administration. The tax question really needs an accountant. We handle the mortgage side around whatever structure you and your accountant agree.
Rental income assessment
Rental income drives lender affordability. Different lenders stress rental income at different levels depending on borrower profile and product. We match applications to lenders whose stress tests give you the borrowing you actually need, rather than just the highest headline offer.
Refinancing existing property
Refinancing releases equity and can fund new acquisitions or refurbishments. It needs to be balanced against gearing, cashflow and long-term strategy. We help model realistic scenarios rather than optimistic ones.
Bridging finance
Bridging finance is a specialist, short-term option often used for auction purchases, refurbishments or chain breaks. Where bridging looks like the right route, we will either arrange it for you or introduce you to a trusted specialist partner, depending on the lender and the structure required. Either way we stay involved, and we will outline the typical costs, risks and exit strategies before you commit to anything.
Planning alongside other professionals
The best portfolio decisions usually involve your accountant, solicitor and sometimes a wider financial planner. We're comfortable working alongside your existing professional team, or introducing you to trusted specialists we work with regularly, so that the mortgage arrangement supports the wider strategy.
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
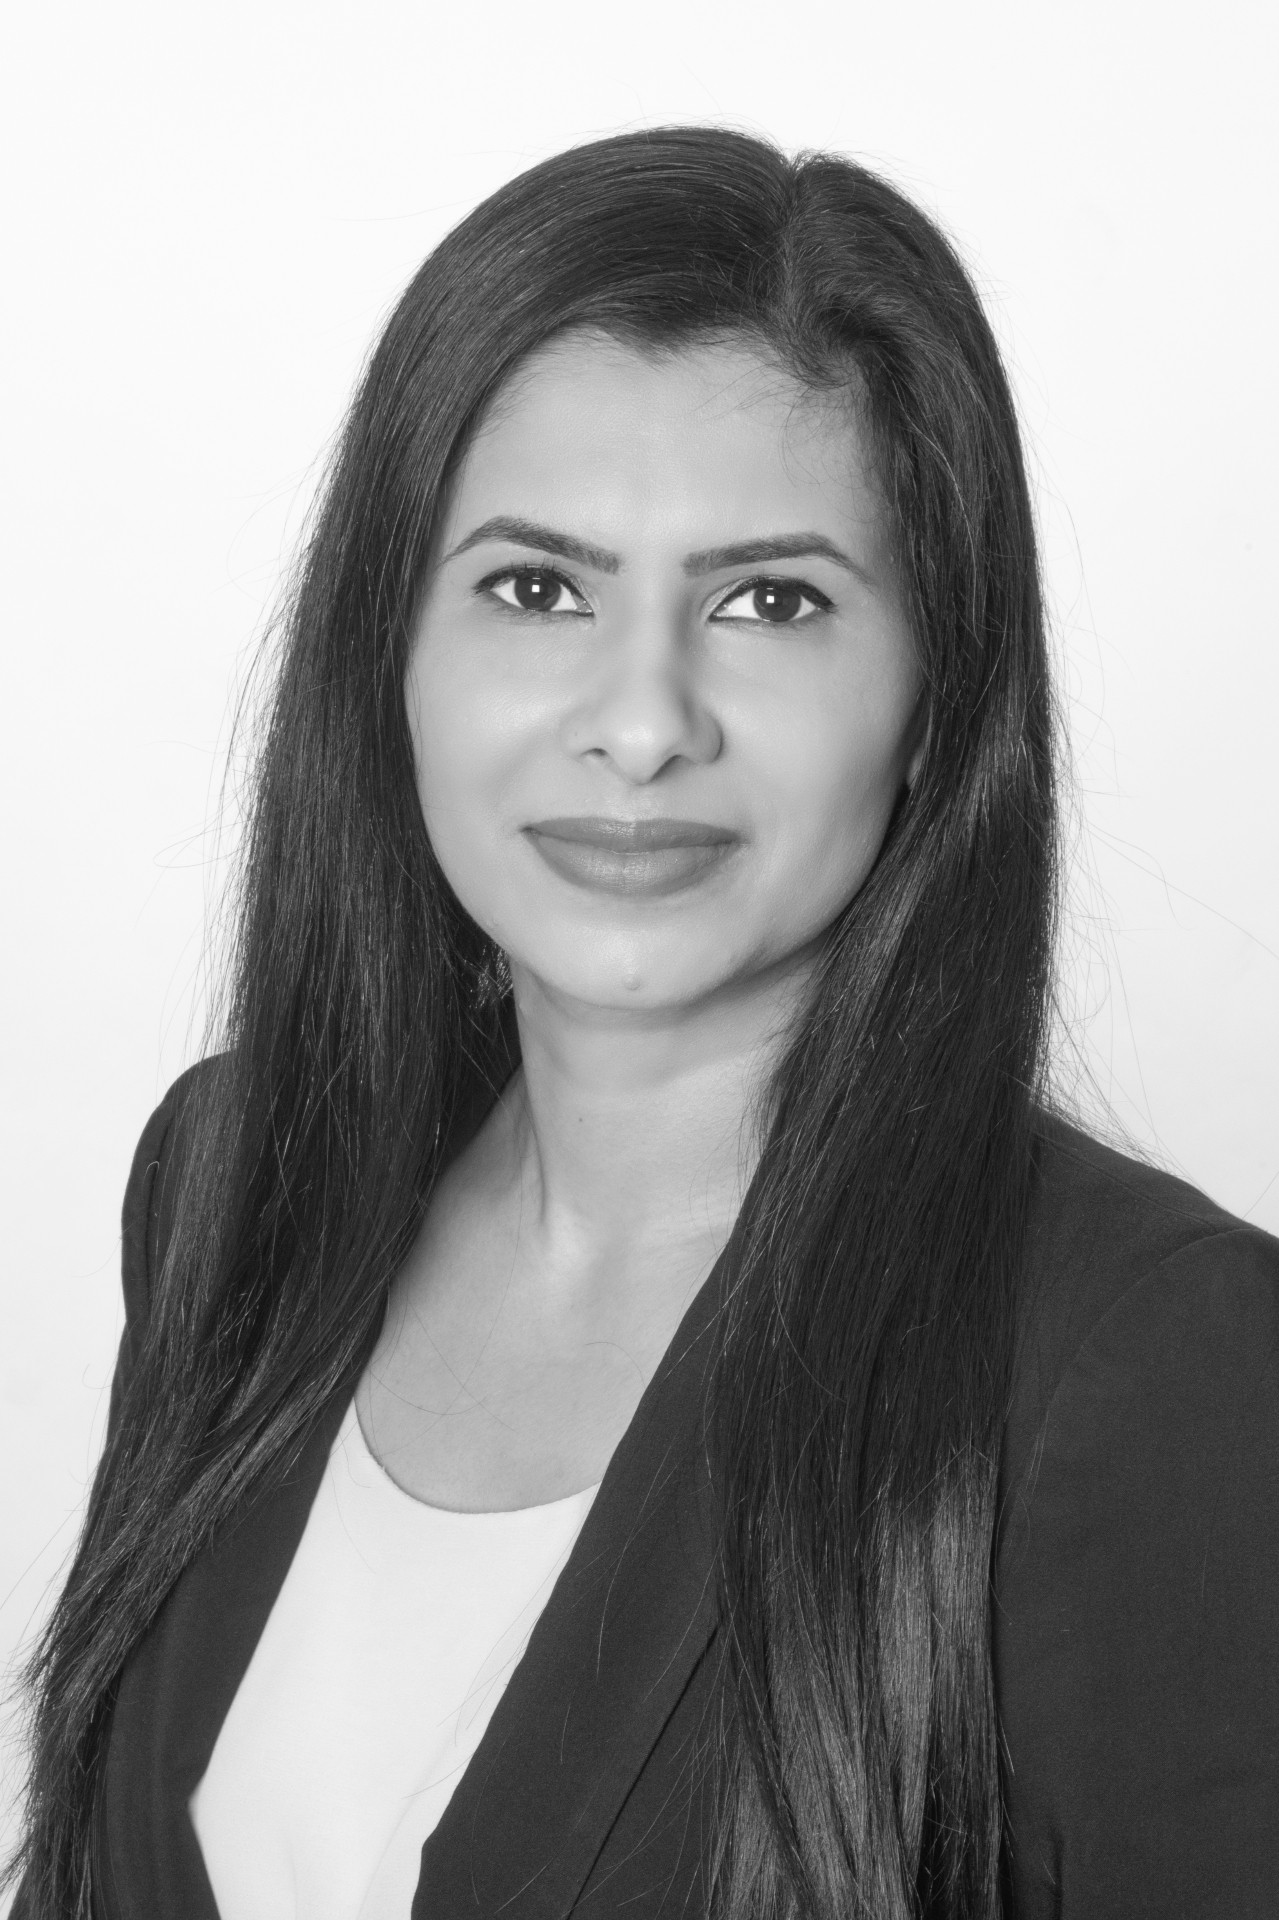
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
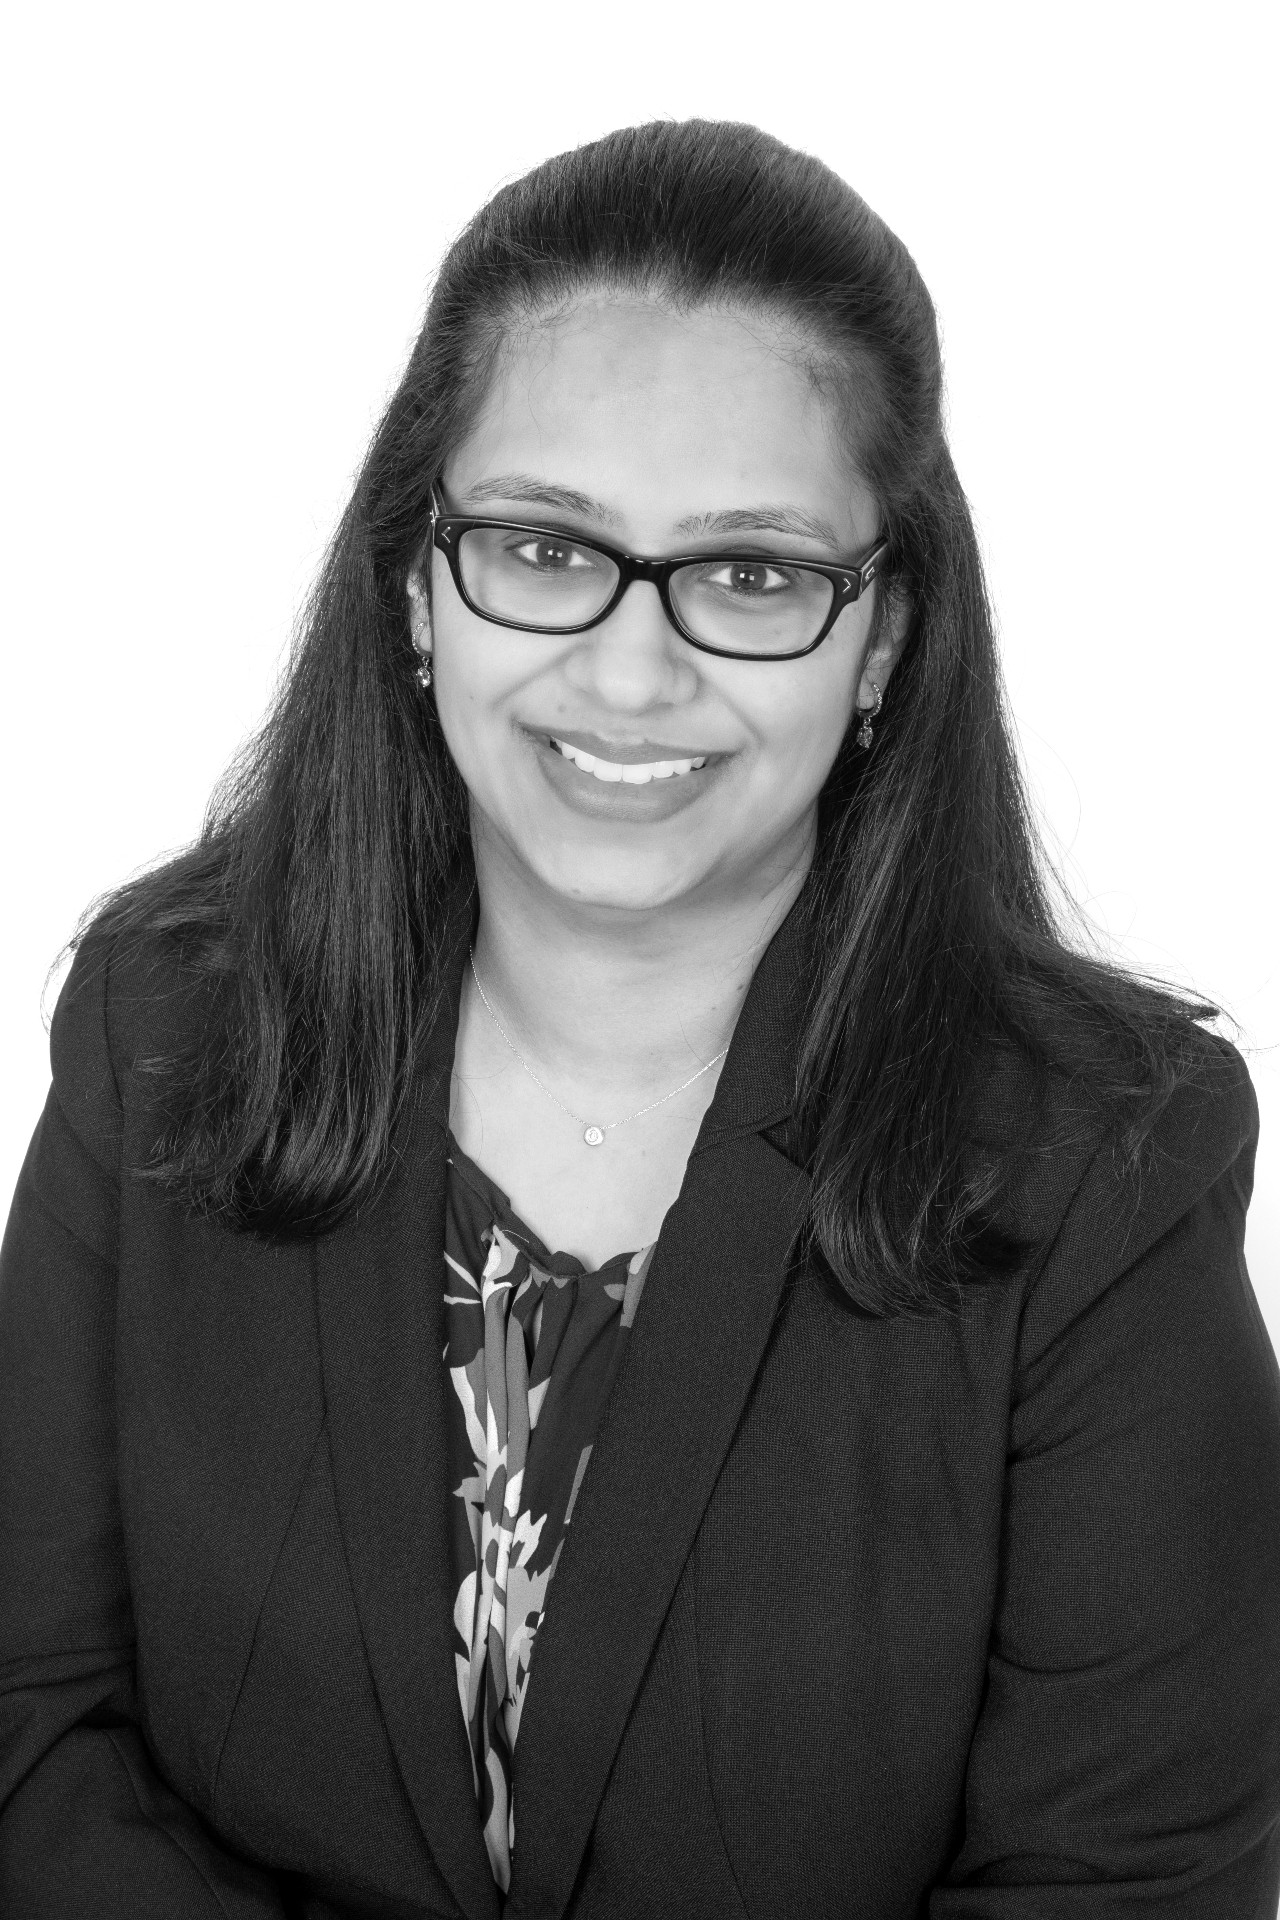
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Frequently Asked Questions
Who counts as a property investor?
Property investor is a broad label covering people who own or plan to own property purely for investment, whether that is a single buy-to-let, a mixed portfolio, HMO properties, commercial units or semi-commercial premises. The right finance depends on the strategy. We work with investors from beginners to those managing established, diverse portfolios across Leicestershire.
What finance options are available to property investors?
Options include residential buy-to-let, HMO mortgages, limited company buy-to-let, portfolio mortgages, commercial and semi-commercial mortgages, and in some cases bridging finance. Each has its own criteria, pricing and risks. We work with investors to identify the most appropriate structure for the specific project and long-term plan rather than reaching for a single default option.
Can I refinance existing properties to fund new purchases?
Often, yes. Releasing equity through a remortgage on existing properties is a common way to fund deposits on new purchases. Feasibility depends on current values, existing loan-to-values, rental coverage and lender criteria. We will help model what is realistically possible and structure a refinance that supports your growth plans without overstretching your overall portfolio.
Can you help if my case is more complex?
Yes. A large part of our work involves cases that do not fit a standard tick-box assessment, including self-employed and company director income, portfolio landlords, limited company structures, high-net-worth borrowers and applications with unusual property or income profiles. We take the time to package the case properly and place it with a lender that understands it, which often makes the difference between a decline and an offer.
Is limited company borrowing better for investors?
For many landlords with several properties, a limited company structure can be tax-efficient, but it also brings more cost and complexity. The right answer depends on your personal tax position, plans and portfolio size. We can advise on the mortgage side and always recommend independent tax advice from a qualified accountant before making structural decisions.
How do lenders view a growing portfolio?
Lenders assess portfolio landlords on overall gearing, cashflow across all properties, geographical spread and existing rental performance, not just the new purchase. Presentation matters. We help structure applications, prepare portfolio schedules clearly, and target lenders whose criteria genuinely support your growth plans rather than making applications that could unnecessarily affect your credit profile.