First-Time Buyer Mortgages in Leicester
Buying your first home should feel exciting, not overwhelming. We explain deposits, affordability and the mortgage process in plain English, then guide you from offer through to completion.
FIRST-TIME BUYER MORTGAGES IN LEICESTER - OVERVIEW
Bina and Tajal personally guide every first-time buyer at Harmony House Mortgages, from your first questions about deposits through to the day you collect the keys. One adviser, one conversation, all the way through.
How much deposit do you need?
Most lenders will consider a mortgage with a deposit of at least 5% of the property price, though 10% or more usually widens your product choice and improves the rates available. A larger deposit lowers your loan-to-value (LTV), which lenders view more favourably.
Understanding affordability
Affordability is how lenders decide what they'll lend you. They look at income (basic, bonus, overtime, self-employed profits), regular outgoings, existing credit commitments, dependants and lifestyle. Different lenders weigh these factors differently, which is why speaking to an adviser is often more revealing than using a generic online calculator.
Mortgage in principle explained
A mortgage in principle (also called an agreement in principle or decision in principle) is a written indication from a lender of how much they might lend you. It usually involves a soft credit check and doesn't affect your credit score. Estate agents and sellers will often ask to see one before accepting your offer.
Monthly payments
Monthly payments depend on the amount borrowed, the interest rate, the term and whether the mortgage is repayment or interest-only. Most first-time buyers use a repayment mortgage, meaning both the interest and part of the capital are repaid each month, so the balance gradually reduces to zero over the term.
Gifted deposits and where deposits can come from
Deposits typically come from savings, gifts from close family, sale of assets, or a combination. Most lenders accept gifted deposits from family, provided the gift is genuine, unconditional and evidenced with a short letter. Some deposit sources are more restricted, so it's worth checking with your adviser before committing to a purchase.
Shared ownership
Shared ownership schemes allow you to buy a share of a property (usually between 25% and 75%) and pay rent on the remainder. It can be a genuine route onto the ladder, but it comes with specific rules and considerations. We can talk through whether it might suit your situation.
Fees and costs of buying
- Mortgage valuation and any additional survey
- Solicitor or conveyancer fees, plus disbursements and searches
- Lender arrangement or product fees, where applicable
- Stamp Duty Land Tax, depending on the property price and current thresholds
- Removals, insurance and initial setup costs in the new home
What happens after your offer is accepted
Once your offer is accepted, we help you finalise your mortgage application, instruct the lender valuation, and coordinate with your chosen solicitor. Your solicitor handles the legal work: searches, contracts, exchange and completion. We keep in regular contact with everyone involved so nothing falls between the cracks.
Typical first-time buyer timeline
From accepted offer to completion typically takes eight to twelve weeks, though it can be quicker or slower depending on the chain, the lender and how promptly documents come back. We'll give you a realistic view at each stage.
First-time buyer checklist
- Photo ID (passport or driving licence) and proof of address
- Three months' payslips or the latest two years of self-employed accounts / SA302s
- Three to six months of bank statements
- Evidence of your deposit and any gifted funds
- Details of existing credit commitments
- A rough budget for monthly outgoings so we can talk affordability realistically
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
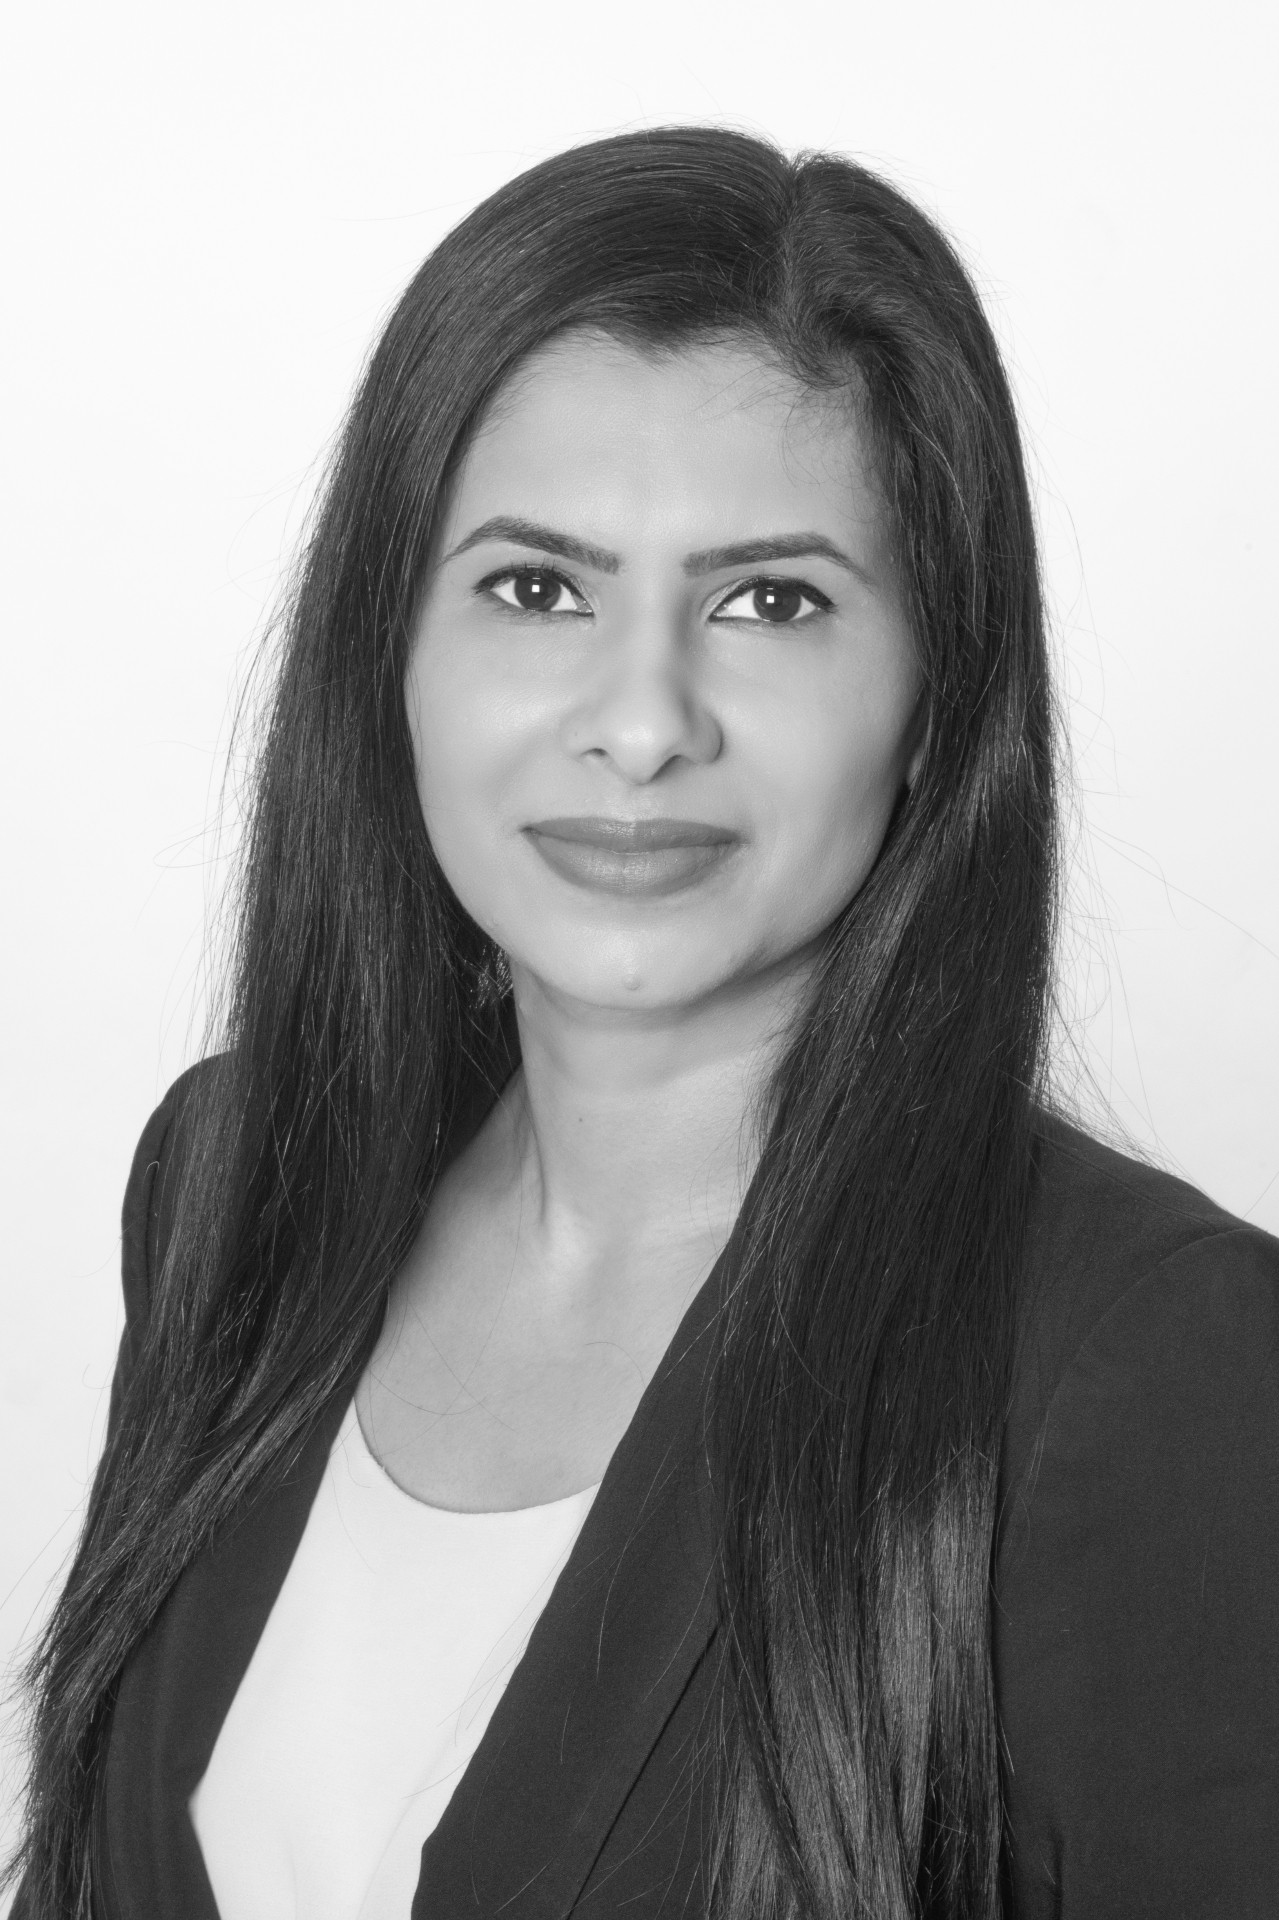
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
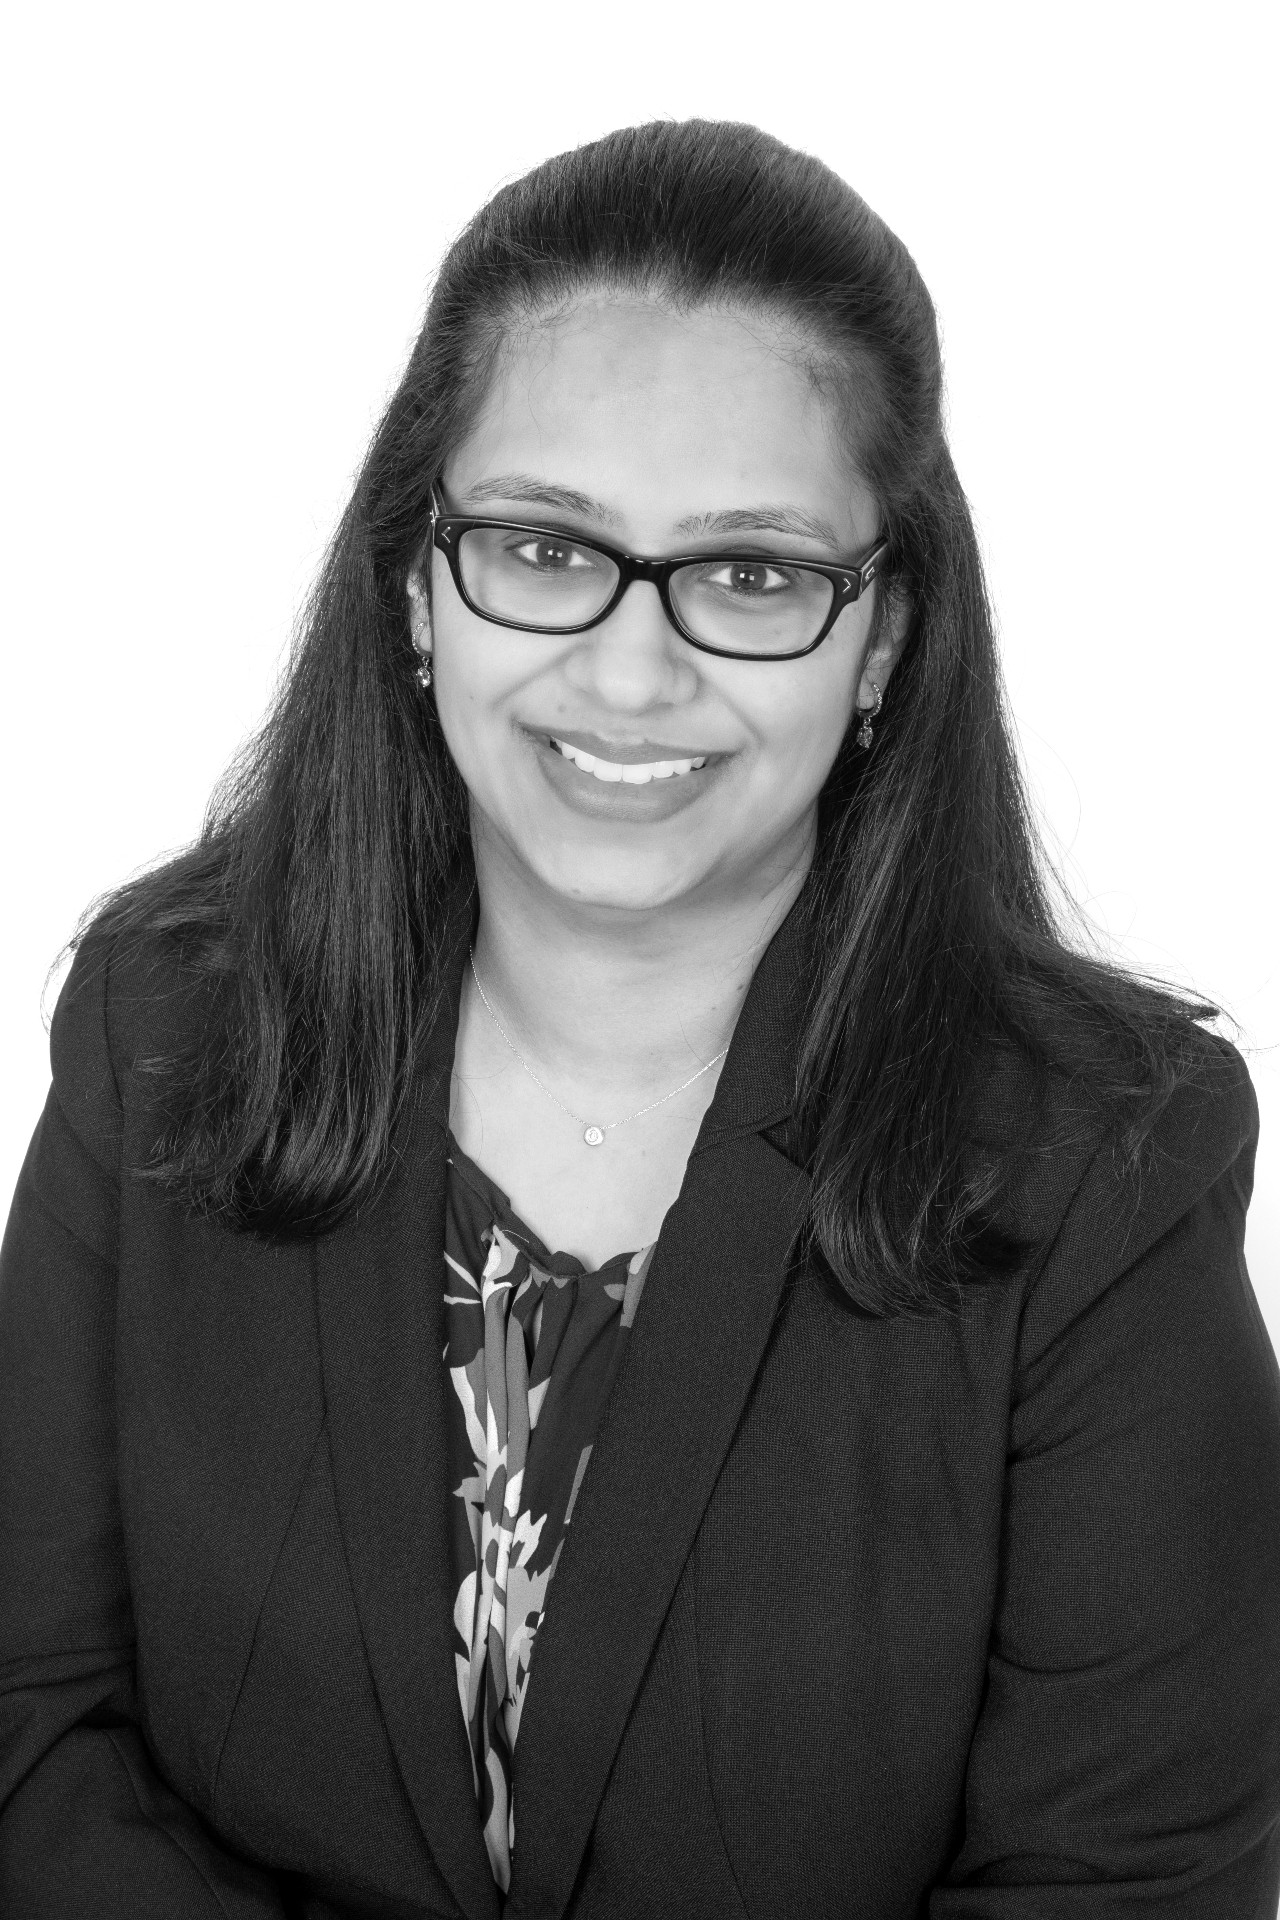
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Frequently Asked Questions
How much deposit do I need as a first-time buyer?
Most lenders look for at least a 5% deposit of the property price, though a 10% or larger deposit usually opens up a wider choice of products and better rates. Your affordability, credit profile and the property itself also matter. We will look at your position and explain what feels realistic and sustainable for you.
How does a mortgage in principle work?
A mortgage in principle is a written indication from a lender of how much they might lend you, based on a soft credit check and some basic details. It helps estate agents and sellers take your offer seriously. It is not a formal mortgage offer, but it is a very useful early step in your buying journey.
Can I use a gifted deposit from family?
Yes, most lenders accept gifted deposits from close family members, provided the gift is genuine, unconditional and properly evidenced. The family member typically signs a short letter confirming they have no claim over the property. We will explain what your lender needs and help you prepare the paperwork so everything runs smoothly on the application.
What is affordability and how do lenders assess it?
Affordability is a lender's view of whether you can comfortably meet the monthly mortgage payments now, and if rates rise. They review income, regular outgoings, existing credit commitments, dependants and lifestyle costs. Different lenders assess this differently, which is one reason working with an adviser can genuinely improve your borrowing options and outcomes.
What fees should first-time buyers budget for?
Beyond the deposit itself, first-time buyers typically budget for a mortgage valuation, solicitor fees, a property survey, mortgage arrangement fee (where applicable), and moving costs. Stamp duty rules can also apply depending on the property value and current thresholds. We will help you understand the likely costs upfront so nothing catches you by surprise later.
What happens after my offer on a property is accepted?
Once accepted, we help you finalise your full mortgage application, instruct the lender valuation and coordinate directly with your chosen solicitor. Your solicitor handles the legal side, including searches and contracts. We keep everything moving between the lender, the solicitor and the estate agent, updating you clearly along the way through to exchange and completion.