Landlord Mortgages
Whether you're an accidental landlord with one property or an experienced investor with a growing portfolio, we help you arrange the right mortgage for the right property at the right time.
LANDLORD MORTGAGES - OVERVIEW
Accidental and experienced landlords
Some landlords deliberately build portfolios. Others end up letting a property after inheriting it or moving in with a partner. Either way, the lending options and expectations differ from a standard residential mortgage, and it's worth taking proper advice rather than assuming your existing lender is the right home for the new arrangement.
Rental income assessment
Lenders typically assess buy-to-let and landlord borrowing against expected rental income. Most apply a stress test comparing the achievable monthly rent to a notional interest rate at 125% to 145% of the mortgage interest cost. Small differences in how lenders calculate this can significantly change how much they'll offer.
Portfolio considerations
Landlords with four or more mortgaged rental properties are often classed as portfolio landlords. Lenders will assess the whole portfolio, loan-to-value, cashflow, geographical spread, void history and rental performance, not just the new property. Presenting your portfolio well matters.
Personal or limited company ownership
Holding property personally or through a limited company can affect tax treatment, costs and long-term flexibility. It's ultimately a tax question, and we'd always recommend speaking with a qualified accountant. We advise on the mortgage side and can work with either structure.
Deposit requirements
Buy-to-let and landlord mortgages typically require at least a 25% deposit, though some lenders start slightly lower and larger deposits usually unlock better rates. The property, rental income and your wider portfolio all influence what's realistic for a specific case.
Choosing the right product
Fixed rates offer predictability, which many landlords value for cashflow planning. Trackers can be lower cost when base rates are benign but come with rate risk. Interest-only structures are common and keep monthly costs down, while repayment options reduce the balance over time. We'll match product features to your strategy.
Existing property remortgages
Refinancing existing rental property can secure better terms, release equity, or support new purchases. We assess your current position honestly and identify lenders whose criteria fit both the property and your wider portfolio.
Growing your portfolio
Growth usually involves a mix of new borrowing and refinancing. We help you plan realistically, model scenarios, and structure applications to keep your options open rather than concentrating your lending unnecessarily with a single provider.
Speaking with an accountant
We are mortgage advisers, not tax advisers. Where structure, tax, incorporation or wider financial planning matters, we work alongside your accountant and other professional advisers to make sure the mortgage arrangement supports the wider plan.
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
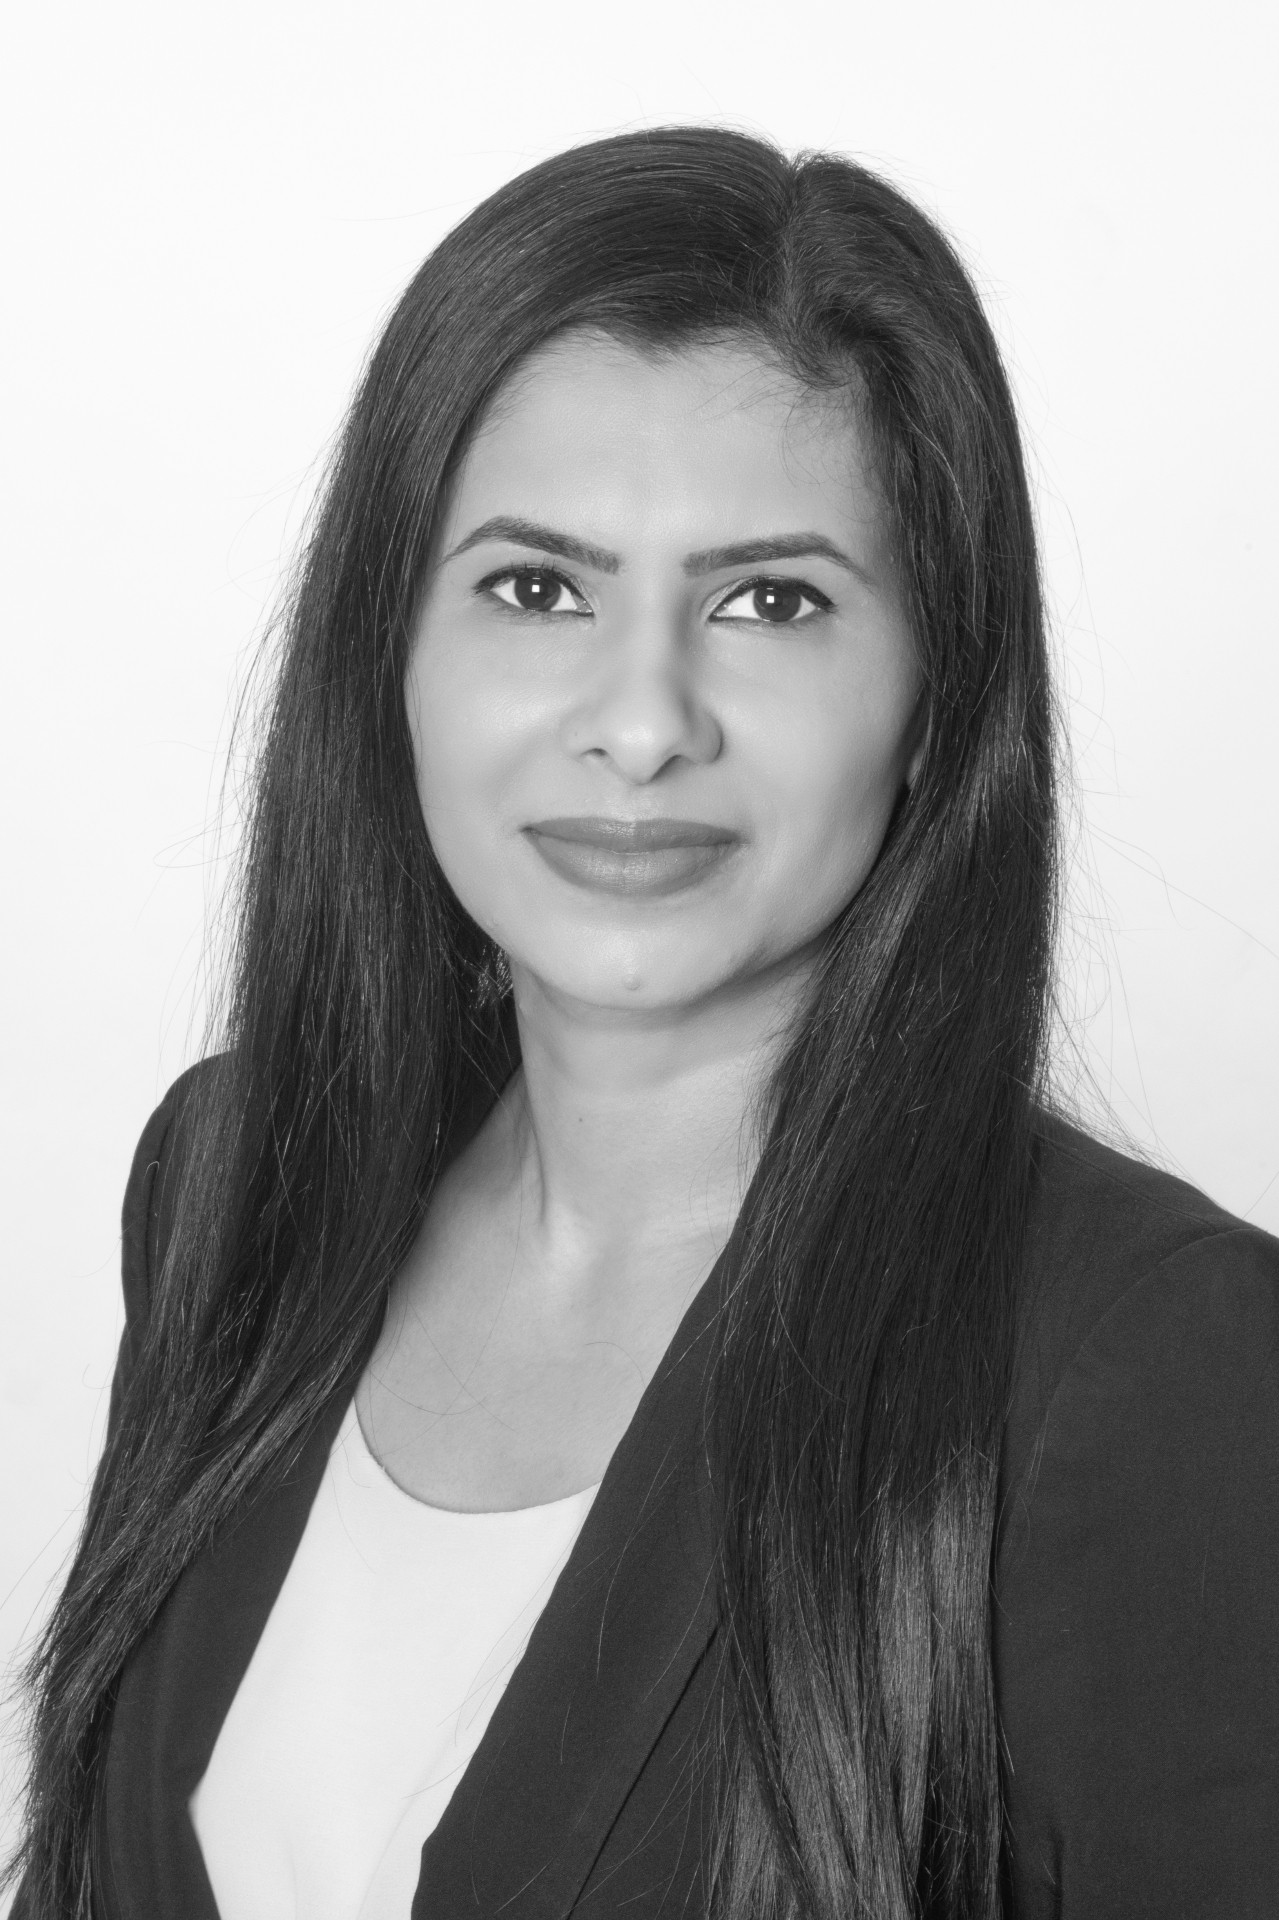
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
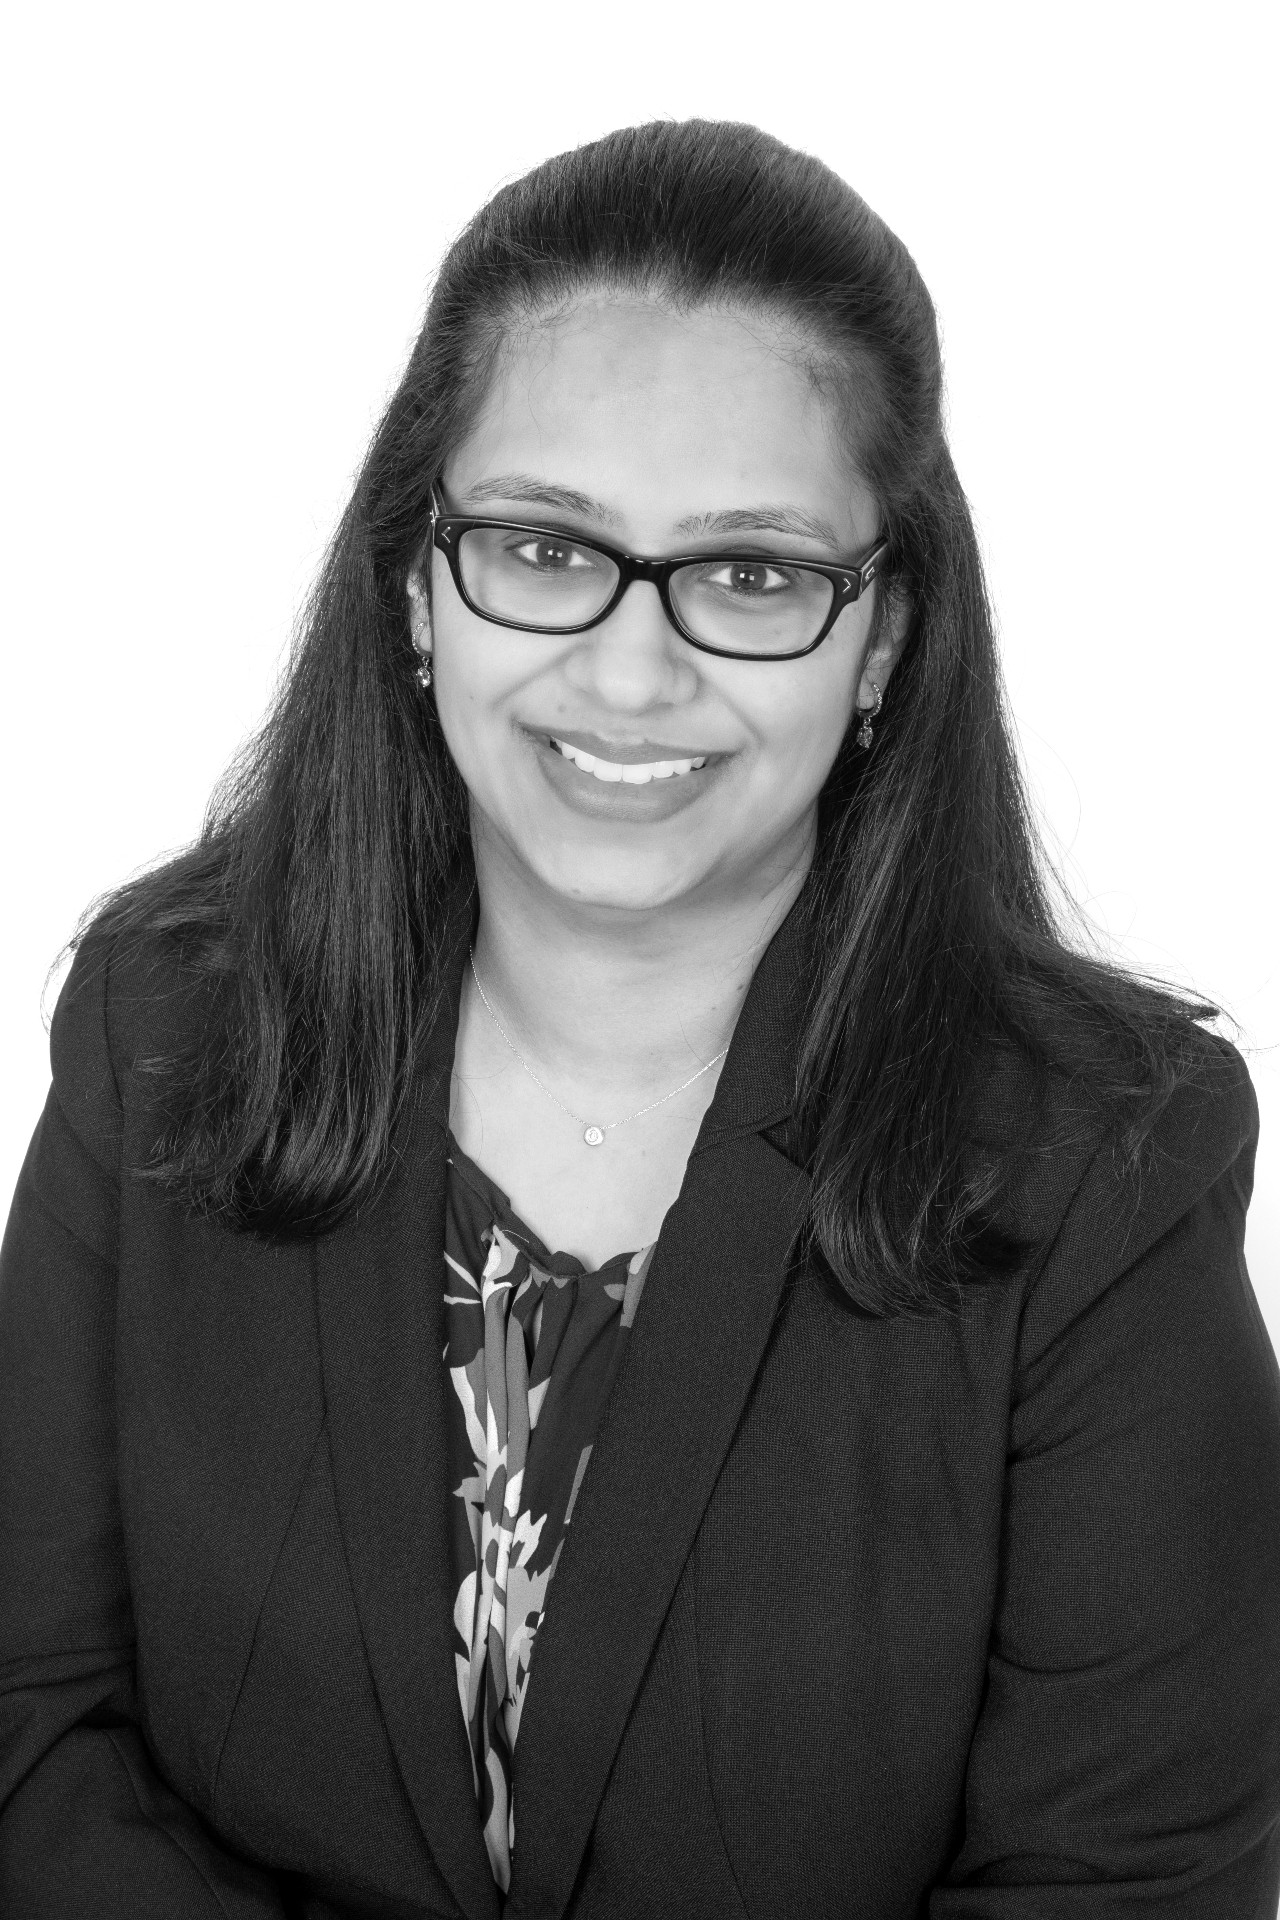
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Frequently Asked Questions
What is a landlord mortgage?
Landlord mortgage is a general term covering buy-to-let and other lending secured against rental property. It can be arranged in your personal name or through a limited company. Lender criteria depend on rental income, deposit, your existing portfolio, and often your personal income too. We help landlords choose the most suitable option for their strategy.
Can I remortgage a property I already rent out?
Yes. Buy-to-let remortgages are very common when the current rate is ending, when raising capital to purchase further properties, or when reviewing terms as rental income changes. We will assess rental income, current loan-to-value and lender appetite before recommending the most appropriate remortgage or product transfer for the property and your wider portfolio.
Is limited company buy-to-let better than personal ownership?
There is no single right answer. Limited company structures can offer tax benefits for some landlords, but come with more complexity, higher product costs and additional administration. The right structure depends on your tax position, plans and income. We can advise on the mortgage side and always suggest speaking with a qualified accountant on tax matters.
How is rental income assessed on a buy-to-let mortgage?
Lenders typically apply a stress test comparing expected monthly rent against a notional interest rate, often 125% to 145% of the mortgage interest, at a stressed rate. The exact calculation varies between lenders and product types. We help identify lenders whose rental coverage tests fit the specific property and rent achievable in the local market.
What if I own several rental properties?
Portfolio landlords, often defined as owning four or more mortgaged rental properties, face additional lender scrutiny of the whole portfolio. Lenders assess overall gearing, cashflow and property spread. We work with portfolio landlords to structure applications carefully, identify lenders comfortable with the wider position and present the full portfolio in the strongest, clearest possible way.
Do I need a solicitor and accountant for a buy-to-let?
Yes. A solicitor handles the legal side of the purchase or remortgage, and an accountant advises on the tax implications of holding rental property personally or through a company. We focus on the mortgage advice and coordinate closely with your chosen professionals to keep the transaction on track and everyone properly informed throughout.