Mortgage Options for Homeowners
Whether you're moving home, borrowing more, changing your mortgage term, or restructuring joint borrowing, we help you weigh the options and choose the route that fits your life.
MORTGAGE OPTIONS FOR HOMEOWNERS - OVERVIEW
Mortgages for existing homeowners
Once you own a home, your mortgage rarely stays the same forever. Rates end, circumstances change, and life brings new priorities. Our role is to keep your mortgage arrangements aligned with those changes, without making it feel like a constant admin task.
Moving home
Moving usually means arranging a new mortgage, porting an existing deal, or a combination of the two. The right choice depends on the rate you have, any early repayment charges, whether you're borrowing more or less, and the timing of your sale and purchase.
Borrowing more
Borrowing more against your home might fund home improvements, a family event, or other significant costs. Options usually include a further advance from your current lender or a full remortgage. We compare both so you can see which offers better overall terms.
Changing mortgage term
Extending the term can reduce monthly payments and ease pressure on the household budget, but you'll typically pay more interest overall. Shortening the term does the opposite. Any term change is subject to lender affordability assessments and your wider circumstances.
Reviewing rates
Even if you're not in the market for anything new, an annual review of your mortgage rate and structure is worthwhile. Lender criteria and product ranges change constantly, and small adjustments can make a real difference over the life of the loan.
Joint mortgages
Joint mortgages are common between partners, family members and, occasionally, friends buying together. All named applicants are usually jointly and severally liable, meaning each is responsible for the whole mortgage. It's worth understanding the practical implications of that from the start.
Changes to employment or income
Moving from employment to self-employment, taking a career break, or a big change in household income can all affect your mortgage options at review time. We help you plan around those changes and identify lenders whose criteria fit your current situation.
Divorce and separation considerations
Separation often means restructuring joint borrowing, transferring the mortgage to one party or arranging a new mortgage entirely. These decisions carry legal and tax implications, and independent legal advice is important. On the mortgage side, we can help you understand what's affordable once the legal picture is clearer.
Improving affordability
Simple steps, reducing existing commitments, closing unused credit accounts, avoiding new credit before applying, can materially improve how a lender views your application. Where useful, we'll suggest practical steps in advance of a formal application.
Staying in your home
Not every mortgage decision means moving. You can often restructure through a remortgage, product transfer, further advance or term change without leaving the home you love. We'll always look at the do-nothing baseline honestly, so any change we recommend is worth making.
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
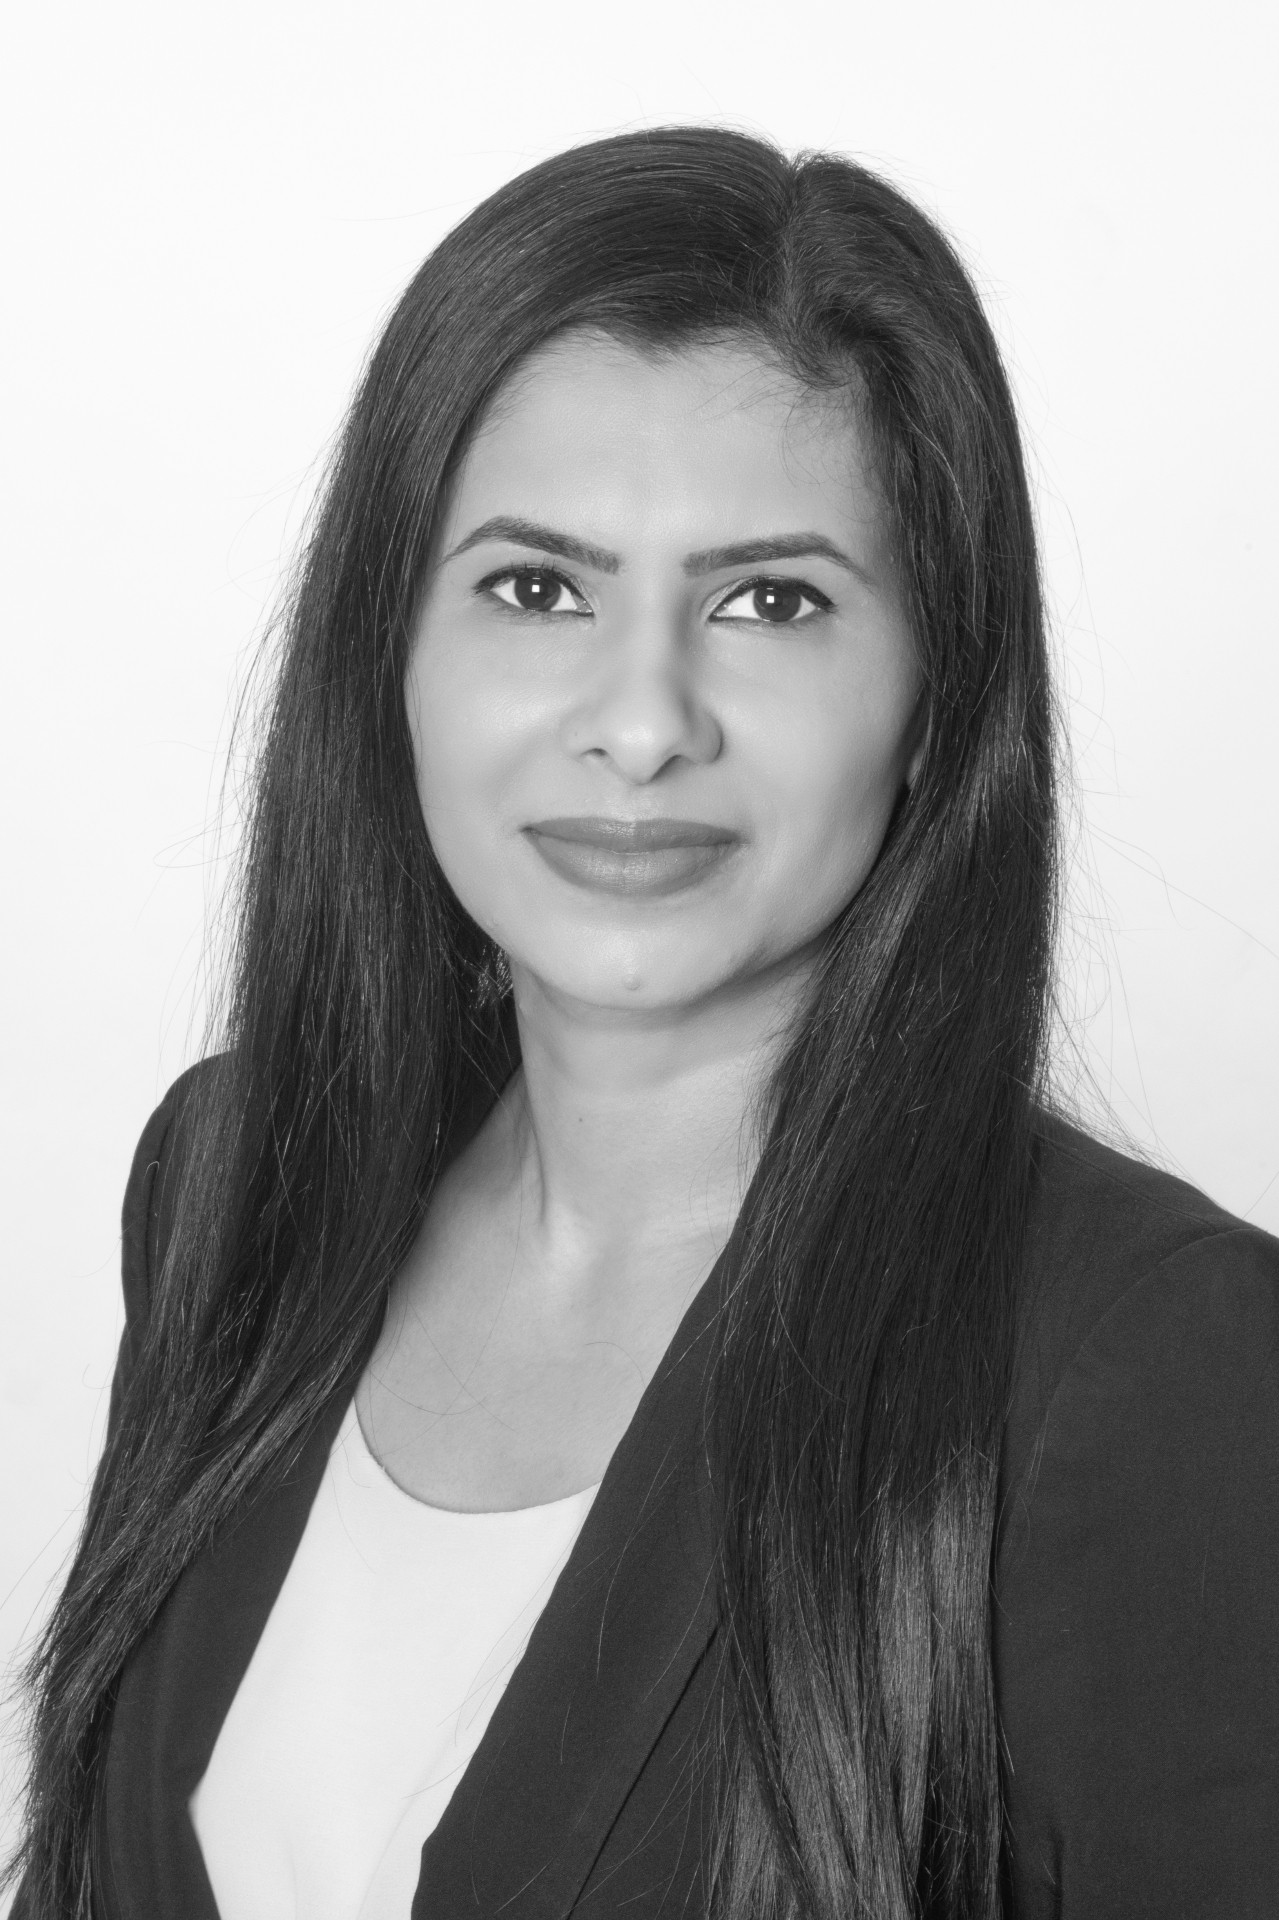
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
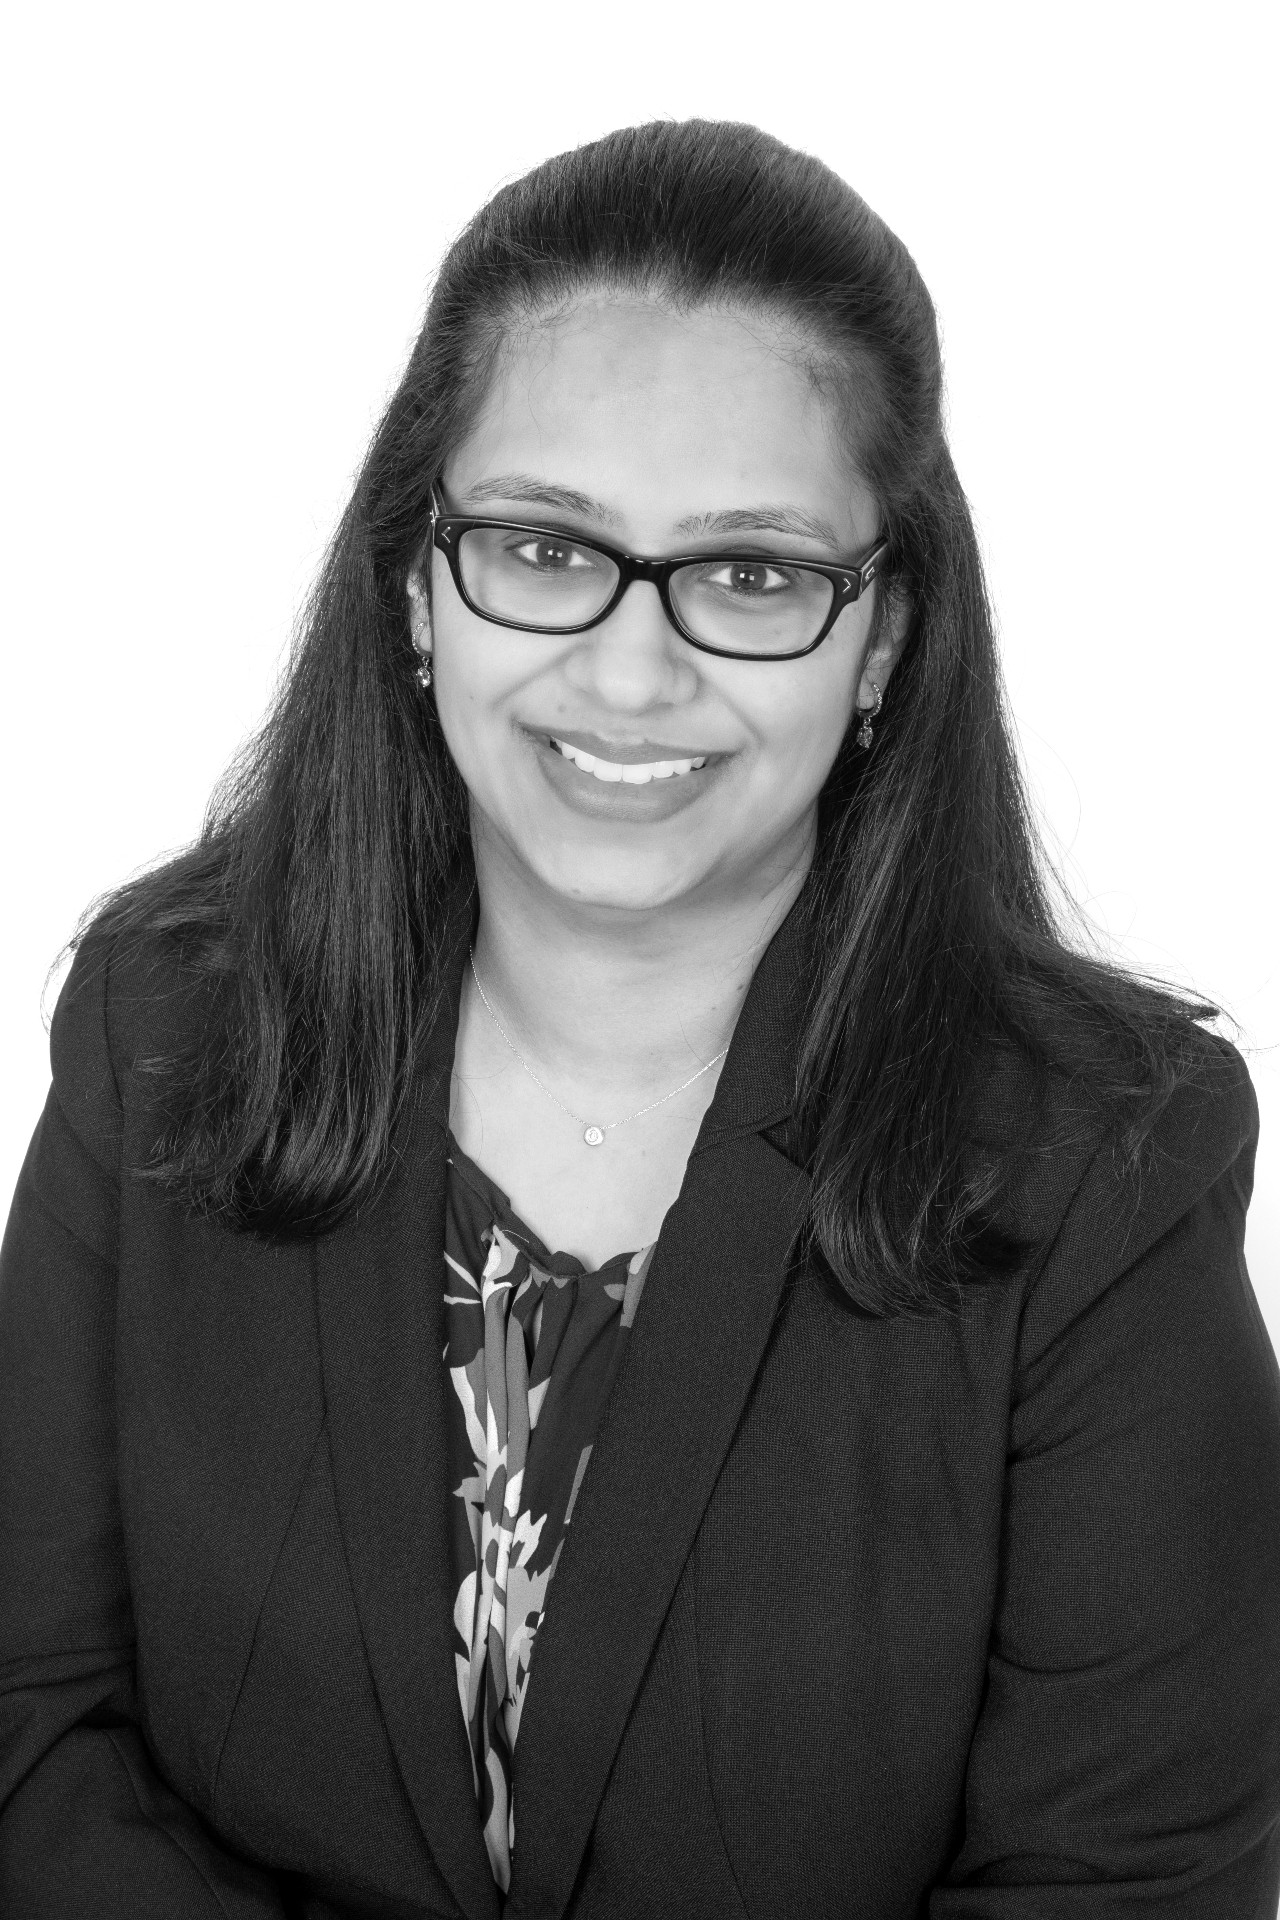
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Frequently Asked Questions
What is a homeowner mortgage?
Homeowner mortgage is a general term for the residential mortgage arrangements available to people who already own a home. This includes remortgaging, borrowing more against your property, changing the mortgage term, moving home or restructuring joint borrowing. The best option depends on your goals, current mortgage, income and long-term plans, which we discuss in detail.
Can I borrow more on my existing mortgage?
In many cases yes, subject to affordability, your loan-to-value and lender criteria. This is often called a further advance and can fund home improvements, major life costs or other needs. We compare a further advance with a full remortgage to a new lender, and recommend whichever route offers the most suitable overall terms.
Can I change the term of my mortgage?
Often, yes. Extending the term can reduce monthly payments, though you may pay more interest overall. Shortening the term does the opposite, saving interest but increasing monthly costs. Any term change is subject to lender affordability rules and your circumstances. We will help you understand the long-term impact before you commit either way.
What happens to a joint mortgage after divorce or separation?
Joint mortgages after separation can be transferred to one party, refinanced, or the property sold. Each route has legal, tax and affordability implications, and lenders will reassess borrowing based on the remaining applicant. We are not solicitors and cannot give legal advice, but we can help you understand mortgage options once decisions have been made.
How do I improve my mortgage affordability?
Reducing existing credit commitments, closing unused accounts, avoiding new credit before applying, and stable, evidenced income all support affordability. A larger deposit or lower loan-to-value also helps unlock better rates. We can review your position in advance and, where useful, suggest simple, practical steps to strengthen your application before it goes to the lender.
Can I stay in my current home and restructure the mortgage?
Usually, yes. You can restructure through a remortgage, a product transfer, a further advance or term changes with your current lender, all without moving. Which is most suitable depends on your circumstances, your existing rate and any early repayment charges. We will run through the options and recommend the route that suits you best.