Equity Release Advice in Leicester
Balanced, thoughtful equity release advice, explaining lifetime mortgages, lump sum and drawdown options, voluntary repayments and the impact on your estate and family.
EQUITY RELEASE ADVICE IN LEICESTER - OVERVIEW
What equity release is
Equity release is a way of accessing some of the value tied up in your home without needing to sell it. In the UK, the most common form is a lifetime mortgage. Home reversion plans exist but are far less common today. Both fall under the broader umbrella of equity release.
Lifetime mortgages
A lifetime mortgage is a loan secured against your home. You retain ownership, and can usually live there for the rest of your life or until you move into long-term care. Interest can roll up, be paid monthly, or be reduced through voluntary payments, depending on the plan chosen.
Lump sum versus drawdown
A lump sum plan releases all the funds at once. A drawdown plan releases an initial amount and allows you to take further sums later, up to an agreed limit, with interest only accruing on money you actually draw. Drawdown often costs less in total interest, but is not always the right choice.
Interest roll-up
On a traditional lifetime mortgage with no monthly payments, interest rolls up and is added to the loan. Over time this can significantly increase the balance owed, which is one of the reasons careful, balanced advice matters and voluntary repayment features are worth considering.
Voluntary repayments
Many modern plans allow voluntary partial repayments, often up to a set percentage of the balance each year, without early repayment charges. This can help control the balance and preserve more equity for your estate, and we'll match product features to your preferences.
No-negative-equity guarantee
Plans meeting Equity Release Council standards typically include a no-negative-equity guarantee, meaning you or your estate will never owe more than the value of your home when it is sold. [Availability depends on the specific plan and provider terms and will be confirmed as part of any recommendation.]
Estate value considerations
Any equity released, plus rolled-up interest, will be repaid from the value of your home. This reduces what remains for your estate. Some plans offer inheritance protection features that ring-fence a portion of the value, and we'll explain these options where relevant.
Benefits eligibility considerations
Releasing money from your home may affect entitlement to means-tested benefits, such as Pension Credit and Council Tax Support. As part of our advice, we'll consider the potential impact carefully and discuss it with you before recommending anything.
Alternatives to equity release
Downsizing, using existing savings or investments, RIO mortgages, later-life residential mortgages, family support, or claiming state benefits you may be entitled to are all possible alternatives. We consider these openly before recommending equity release.
Family and inheritance considerations
Later-life decisions have implications for the people close to you. We strongly encourage involving family in the conversation and are happy for them to join meetings. Open discussion early usually leads to better long-term outcomes for everyone involved.
The advice process
Our process is unhurried. We'll take time to understand your circumstances, discuss alternatives, consider the impact on your estate and any benefits, and involve family where appropriate. Independent legal advice is required and, where useful, we can help coordinate with your solicitor.
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
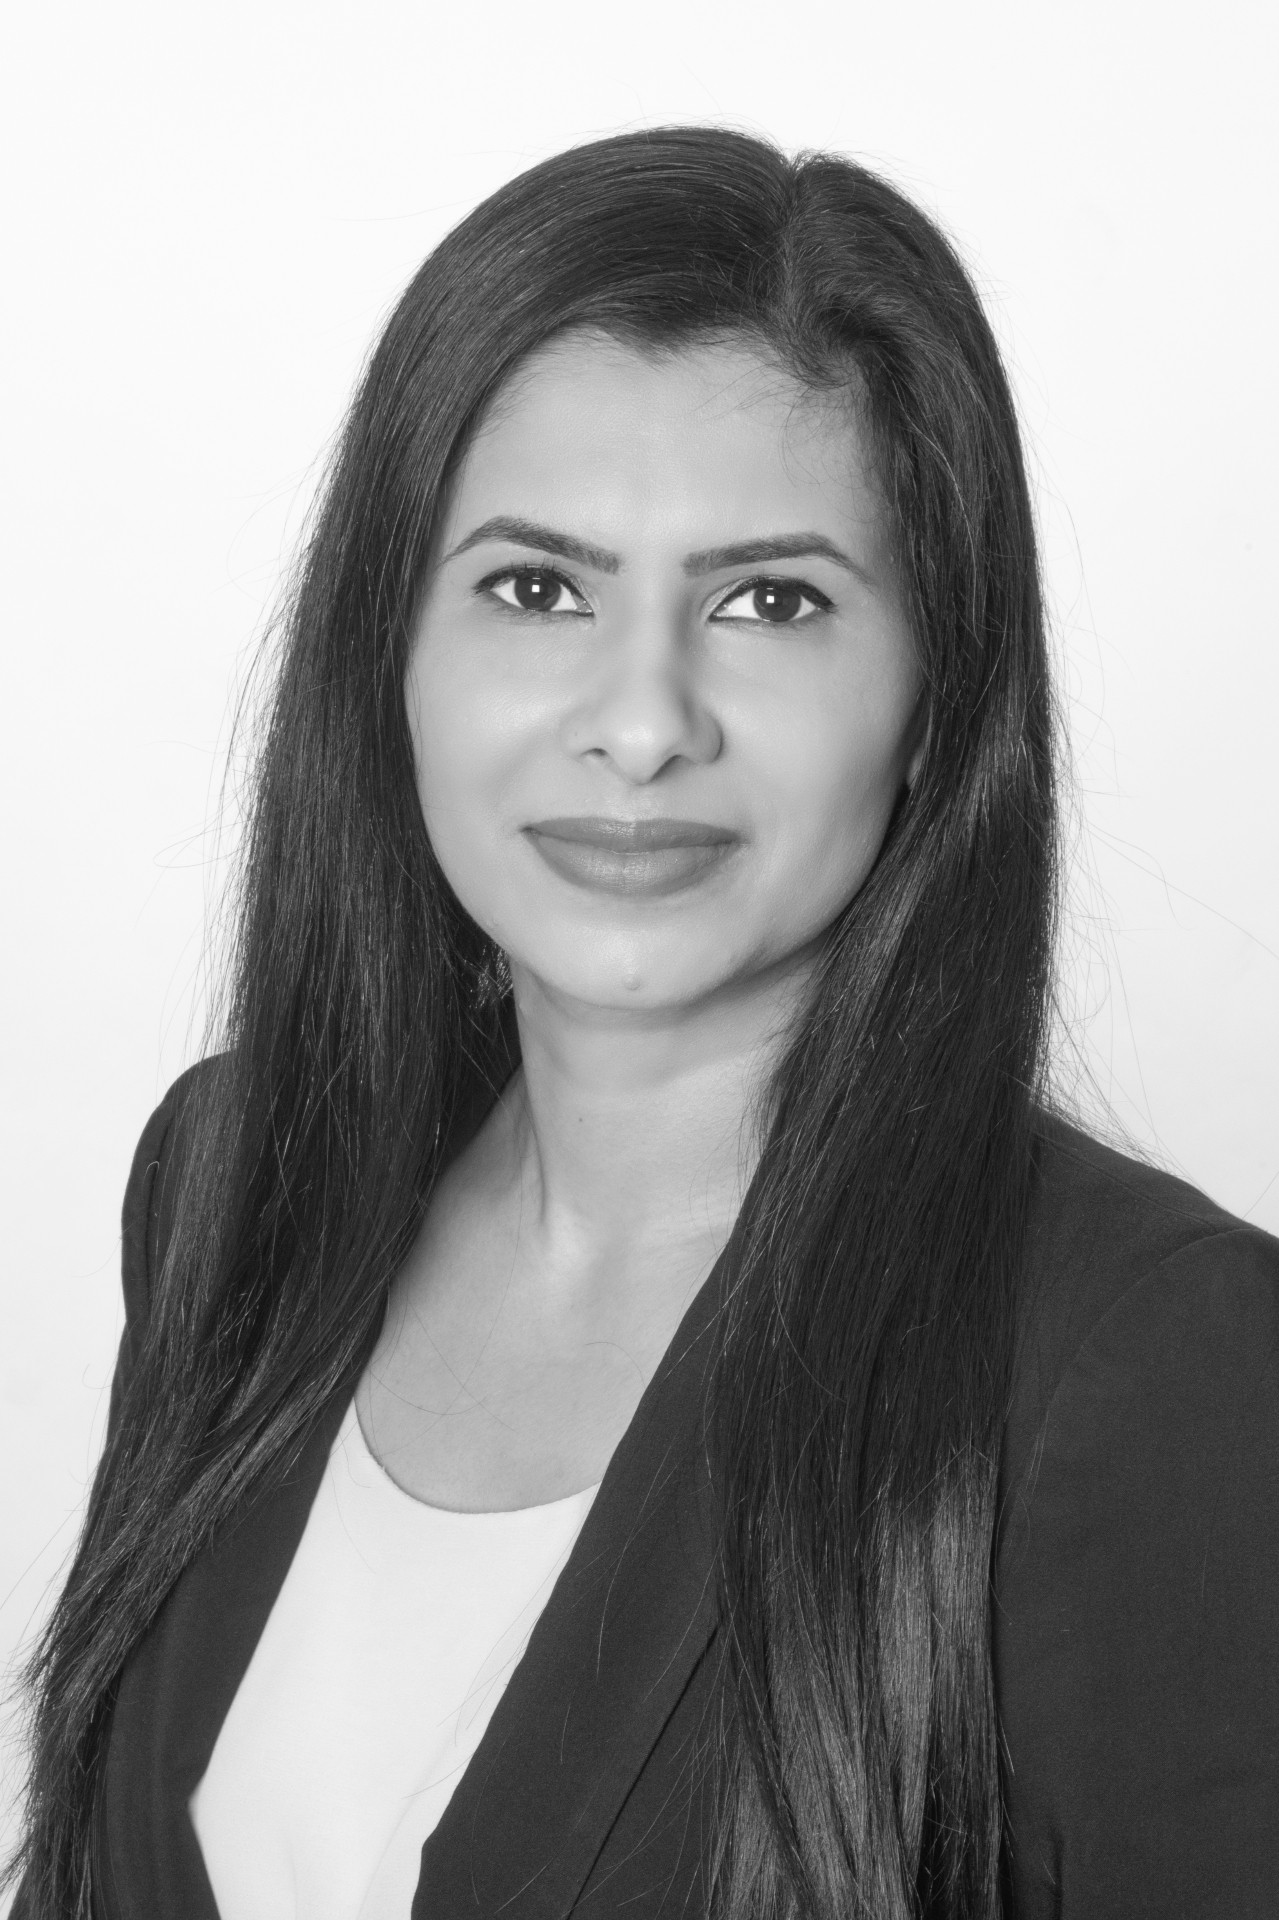
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
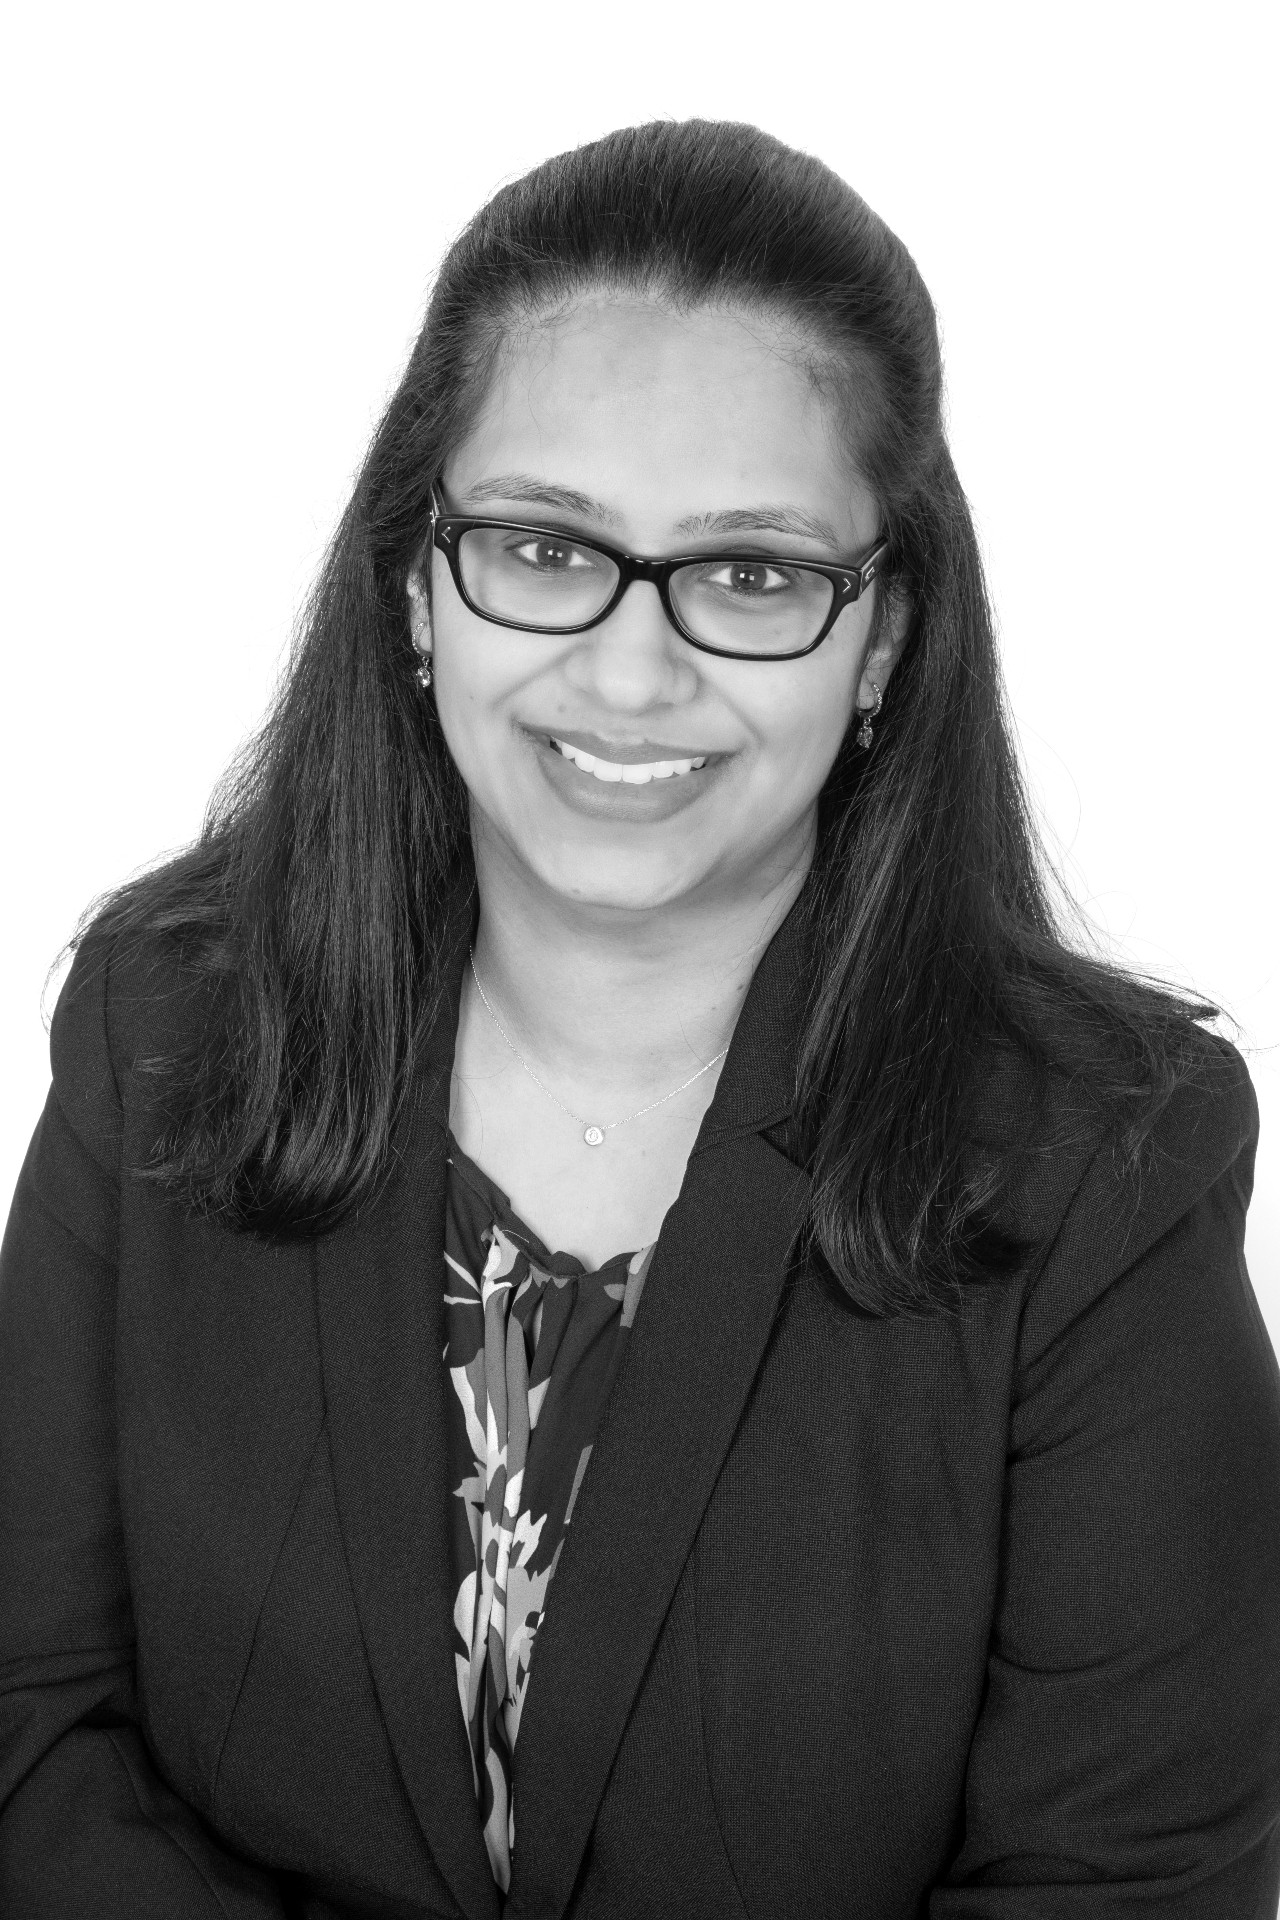
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Frequently Asked Questions
What is equity release?
Equity release is a way of accessing some of the value tied up in your home without needing to sell it. The most common form is a lifetime mortgage, secured against your home, with no compulsory monthly payments. Interest is added to the loan and repaid from your estate, usually when you die or move into care.
What is a lifetime mortgage?
A lifetime mortgage is a loan secured against your home. You retain ownership and can usually live there for the rest of your life or until you move into long-term care. There are typically no required monthly payments, and interest is added to the loan over time. The debt is repaid from the sale of the property.
Lump sum or drawdown - which is better?
A lump sum releases the full amount at once. A drawdown facility lets you take an initial sum and further amounts later, up to an agreed limit, with interest only accruing on funds actually drawn. Drawdown often costs less in interest overall but is not always available or right. We will discuss which suits your plans.
Can I make voluntary repayments on a lifetime mortgage?
Many modern lifetime mortgages allow voluntary partial repayments, often up to a set percentage of the balance each year, without early repayment charges. This can help control the growing balance and preserve more equity for your estate. Product features vary between providers, so we will match plan features carefully to your personal preferences and priorities.
What is a no-negative-equity guarantee?
A no-negative-equity guarantee, offered on plans meeting Equity Release Council standards, means you or your estate will never owe more than the value of your home when it is sold. [Availability depends on product and provider terms.] We will confirm whether this feature is present on any specific plan before we recommend it to you.
What are the alternatives to equity release?
Alternatives include downsizing, using savings or investments, a retirement interest-only (RIO) mortgage, a standard later-life residential mortgage, help from family, or state benefits you may be entitled to but are not currently receiving. Equity release is not always the right answer. We will look openly at all suitable alternatives before recommending any later-life borrowing route.