Critical Illness Cover Advice in Leicester
A tax-free lump sum on diagnosis of a defined serious illness, giving you space to focus on recovery rather than finances.
CRITICAL ILLNESS COVER ADVICE IN LEICESTER - OVERVIEW
What critical illness cover is
Critical illness cover pays a tax-free lump sum if you're diagnosed with one of a defined list of serious medical conditions during the policy term and survive a short qualifying period.
Conditions typically covered
Most policies cover conditions such as cancer meeting the policy definition, heart attack, stroke, multiple sclerosis and major organ transplant. The specific list and severity requirements vary between insurers.
Why definitions matter
Two policies covering "cancer" will not necessarily pay out on the same diagnosis. The strength of the definitions and the number of conditions covered are as important as the price.
Standalone vs combined policies
Critical illness cover can be arranged alongside life insurance (paying out on the first event) or as a separate policy. Combined policies are usually cheaper; separate ones can pay out twice.
Children's cover
Most policies include some level of children's critical illness cover automatically. The definitions and sums assured vary widely, so it's worth understanding what is actually included.
Choosing a sum assured
A common approach is to arrange enough cover to clear the mortgage, cover a period of lost income and provide for any adjustments to your home. We'll help you settle on a sensible amount.
Cost considerations
Premiums are based on age, health, lifestyle, sum assured and term. Because definitions vary, cheapest is rarely best value, we'll compare quality and price side by side.
Big-firm experience. Boutique-level service.
With extensive experience across leading corporate and PLC mortgage environments, Bina and Tajal bring expert knowledge across everything from first-time buyers to complex, high-net-worth and property investment lending.
At Harmony House Mortgages, that expertise is combined with the personal attention and accessibility of a boutique mortgage firm.
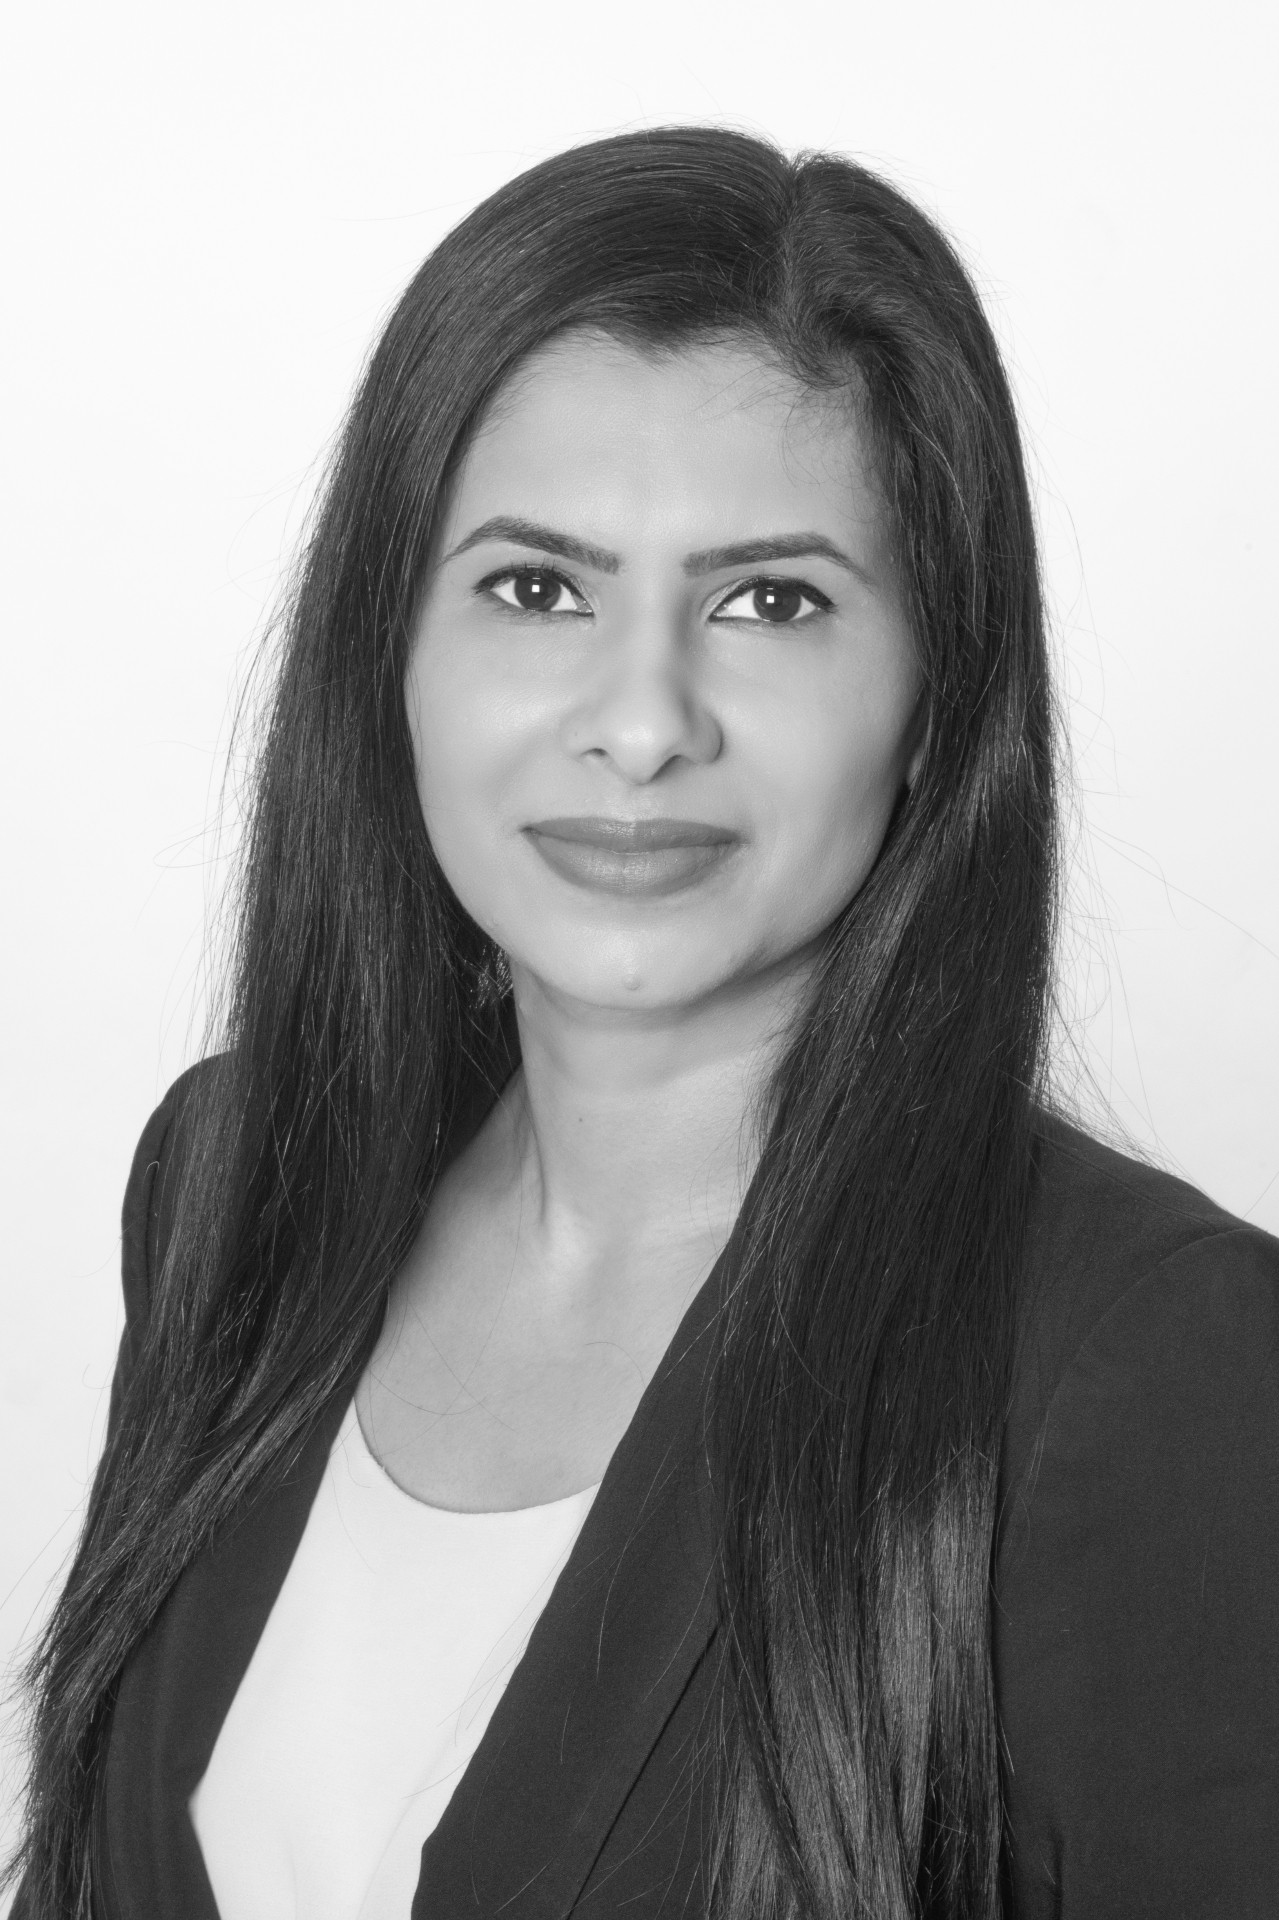
Bina brings extensive experience from the corporate mortgage sector, combining specialist knowledge with a highly personal approach to advice.
She works with clients across the mortgage spectrum, from first-time buyers and home movers to experienced landlords, property investors and high-net-worth individuals with more complex borrowing requirements.
Her strength lies in understanding the bigger picture, navigating complex cases and finding the right lending solution while making the process feel straightforward from start to finish.
When she's not helping clients, Bina is a busy mum of three and knows just how important it is to have someone you can trust when making life's bigger decisions.
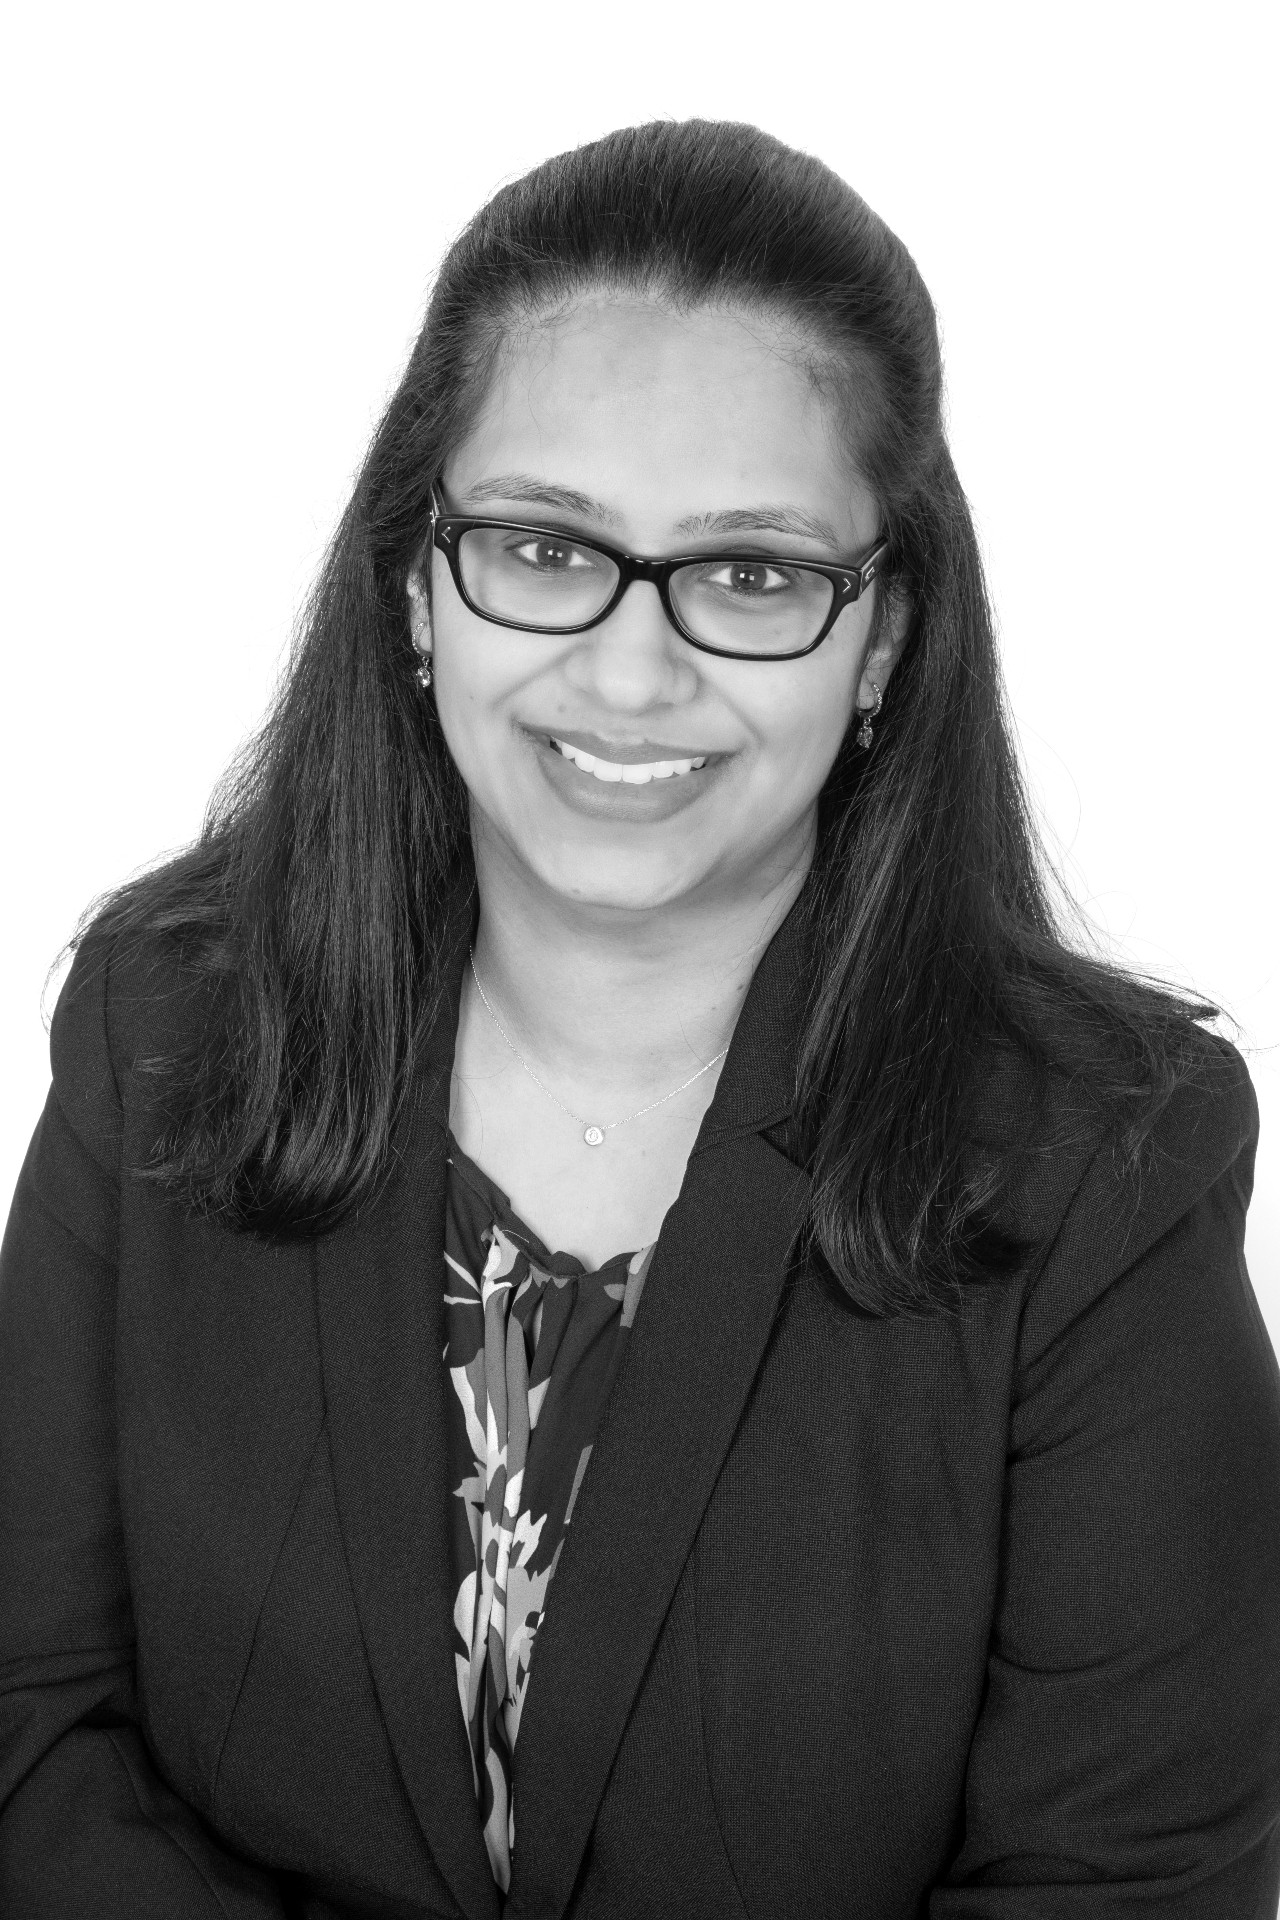
Tajal brings extensive experience from the corporate mortgage world, with a particular strength in navigating complex cases and finding solutions where the straightforward route isn't always the right one.
Her calm, considered approach and attention to detail give clients confidence throughout the process, whether they're remortgaging, self-employed, investing in property or have more specialist borrowing requirements.
Away from mortgages, Tajal is a busy mum of three and enjoys balancing family life with a career she genuinely loves.
Arrange a conversation with an adviser
A relaxed, no-obligation conversation with Bina or Tajal to talk through your options.
Explore more from Harmony House Mortgages
Frequently Asked Questions
What conditions does critical illness cover include?
Most policies cover a defined list of serious conditions such as certain cancers, heart attack, stroke, multiple sclerosis and major organ transplant. The specific list, definitions and required severity vary between insurers. We compare the policies carefully and explain what is and is not covered, so you understand the strength of the protection you are buying.
How is critical illness cover different to life insurance?
Life insurance pays out on death during the term, while critical illness cover pays out on diagnosis of a defined serious illness that you survive by a short qualifying period. Many clients hold both, either as separate policies or as a combined policy that pays on the first event. Each approach has trade-offs we will explain.
Should I choose a combined or standalone policy?
Combined life and critical illness policies pay out once on the first event and are usually cheaper. Standalone critical illness cover can pay out separately from life insurance, so you could potentially receive both. The right choice depends on budget and priorities, and we will always model both options and recommend which best fits your situation.
Does critical illness cover include children?
Most policies include a level of children's critical illness cover automatically, paying a smaller lump sum if a child is diagnosed with a covered condition. The definitions, age limits and pay-out amounts vary widely between insurers. We will show you what is actually included so you understand the level of children's cover you are receiving.
Will pre-existing conditions be covered?
Insurers ask detailed health, lifestyle and family history questions and price or exclude accordingly. Pre-existing conditions may be excluded or lead to higher premiums. Being honest on the application is essential. We know which insurers tend to take a more considered view of certain conditions and can target the application accordingly.
How much critical illness cover should I have?
A common approach is to arrange enough cover to clear the mortgage, replace lost income for a meaningful period and cover any adjustments to your home. There is no fixed formula. We will discuss your family, work, mortgage and savings so we can help you settle on a figure that feels appropriate and sustainable in premium terms.